Israel ends the allocation-number pilot and lowers the threshold to NIS 20,000 for 2025
This page records one dated change. For the rules in Israel as they stand today, see the Israel guide →
- Jurisdiction
- Israel
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 20 November 2024
- Effective
- 1 January 2025
- Instrument
- IL-MINISTERIAL-ORDER-KT-11668
- Authority
- שר האוצר (Minister of Finance of Israel), with Knesset Finance Committee approval
- Verified
- Fetched from official source · medium confidence
Israeli VAT-registered businesses issuing or receiving tax invoices above NIS 20,000 before VAT during 2025.
No action required — the NIS 20,000 threshold was superseded by the NIS 10,000 threshold from 1 January 2026 (see il-ctc-alloc-10k-2025), and subsequently by NIS 5,000 from 1 June 2026 (see il-ctc-allocation-number-clearance-2026).
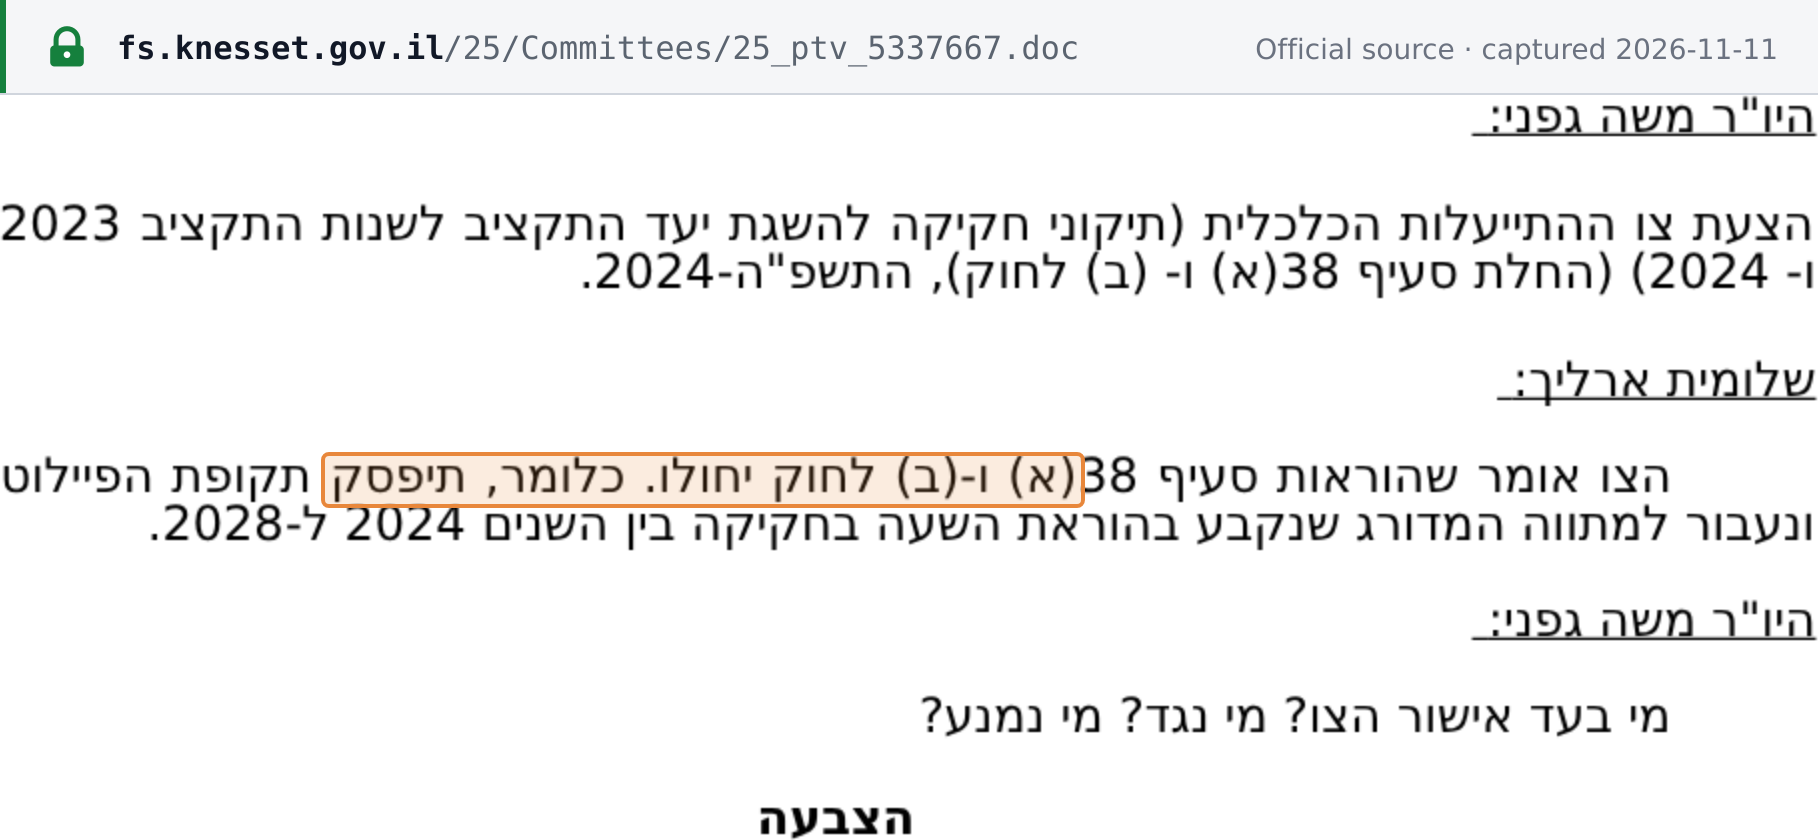
Israel's Minister of Finance, with Knesset Finance Committee approval (20 November 2024), ordered that section 38(a)-(b) of the Economic Efficiency Law 5783-2023 continue to apply after the 2024 pilot. This triggered the statutory step under s.38(b)(1): from 1 January 2025 the CTC allocation-number threshold falls from NIS 25,000 to NIS 20,000 (pre-VAT). The ITA may also refuse an allocation number. The order is reported as KT 11668 of 31 December 2024 (not verified from Reshumot).
What changed in detail
Section 38 of Israel’s Economic Efficiency Law 5783-2023 (Sefer HaChukim 3045) set a stepped schedule for the allocation-number threshold, but section 38(d) made everything after the 2024 pilot conditional: the Minister of Finance, with Knesset Finance Committee approval, could either extend the pilot by one year or order that section 38(a) and (b) apply; if neither was done by 31 December 2024, those subsections would lapse.
The Minister asked the Committee to approve such an order on 31 October 2024. The Committee approved the order applying section 38(a) and (b) on 20 November 2024. As explained to the Committee, the order ends the pilot and moves to the stepped schedule already in the law.
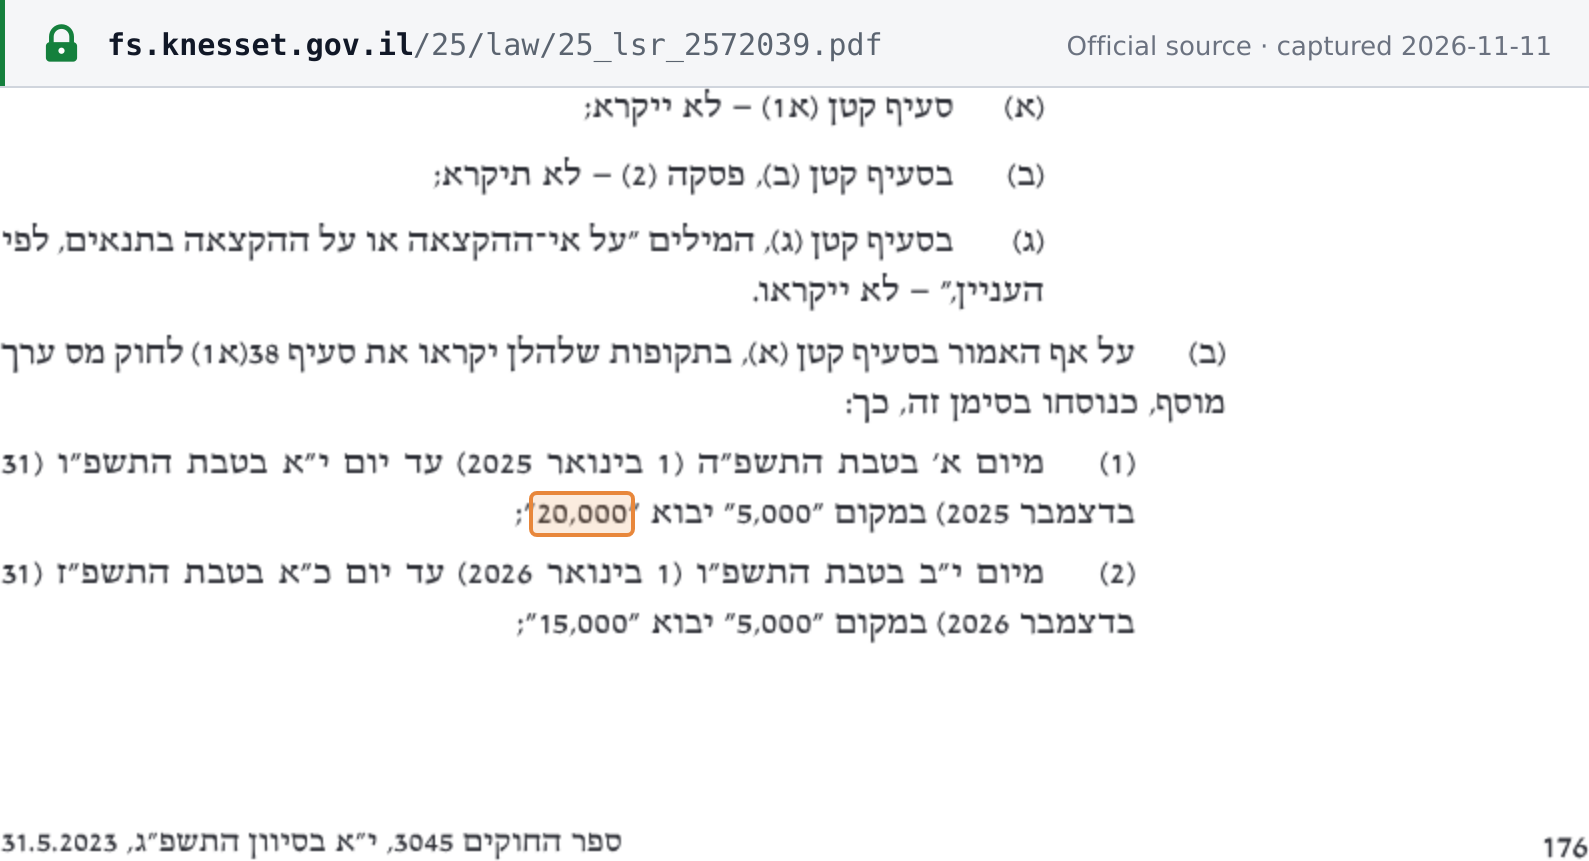
The order does not itself set a figure. The figure is statutory: under section 38(b)(1), from 1 January 2025 to 31 December 2025 the threshold in section 38(a1) of the VAT Law is read as NIS 20,000 instead of NIS 5,000, before VAT. With the pilot over, the Tax Authority may also refuse to allocate a number, subject to the hearing and objection procedure in the law. The order’s Reshumot reference and publication date could not be confirmed from an official text.
What it means
This threshold is spent. NIS 20,000 applied to invoices issued in 2025, replacing the NIS 25,000 pilot threshold of 2024. The original schedule would have gone to NIS 15,000 in 2026; the 2025 Budget Arrangements Law instead set NIS 10,000 from 1 January 2026 and the base NIS 5,000 from 1 June 2026, which is the current threshold.
The more lasting change in this step is the end of the pilot: from 2025 the Tax Authority could refuse an allocation number, not merely issue one.
Proof
מיום א' בטבת התשפ"ה (1 בינואר 2025) עד יום י"א בטבת התשפ"ו (31 בדצמבר 2025) במקום "5,000" יבוא "20,000"From 1 January 2025 to 31 December 2025, instead of '5,000' read '20,000'
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ספר החוקים 3045, י״א בסיוון התשפ״ג (31.5.2023) — חוק ההתייעלות הכלכלית, התשפ״ג-2023, סעיף 38(ב)(1) · fs.knesset.gov.il
הצו אומר שהוראות סעיף 38(א) ו-(ב) לחוק יחולו. כלומר, תיפסק תקופת הפיילוט ונעבור למתווה המדורג שנקבע בהוראת השעה בחקיקה בין השנים 2024 ל-2028.The order says that the provisions of section 38(a) and (b) of the Law will apply. That is, the pilot period will end and we will move to the stepped schedule set in the temporary provision in the legislation for 2024 to 2028.
 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Israel starts invoice allocation numbers at a NIS 25,000 threshold for 2024 effective 5 May 2024