Italy removes landfill and incineration without energy recovery from the 10% VAT rate for waste services
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 31 December 2024
- Effective
- 1 January 2025
- Instrument
- IT-ACT-207-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Operators managing urban and qualifying special waste in Italy, especially landfill operators and incinerators without efficient energy recovery, and the municipalities and businesses they invoice.
No action — in force since 1 January 2025. Waste management service providers must verify that their services still qualify for 10% VAT; landfill operators and incinerators (without efficient energy recovery) must apply the standard 22% rate.
Legge 30 dicembre 2024, n. 207 (Legge di bilancio 2025; GU n. 305 of 31 December 2024, SO n. 43), Art. 1, comma 49, replaced number 127-sexiesdecies of Tabella A, Parte III of DPR 633/1972 from 1 January 2025: the 10% rate covers management, storage and temporary deposit of urban waste and of special waste under Art. 184(2) and (3)(g) of D.Lgs. 152/2006, and management of sewerage and purification plants, but expressly excludes landfilling and incineration without efficient energy recovery, which therefore fall to the standard 22% rate.
What changed in detail
Law 30 December 2024, n. 207, the 2025 Budget Law (Gazzetta Ufficiale n. 305, supplemento ordinario n. 43, of 31 December 2024), Article 1, comma 49, replaces number 127-sexiesdecies of Tabella A, Parte III, of DPR 633/1972, the list of supplies taxed at 10%. It applies from 1 January 2025. The comma states its aims as ecological and energy transition and respect for the waste hierarchy in a circular economy.
The new number covers management, storage and temporary deposit services, as defined in Article 183(1)(n), (aa) and (bb) of D.Lgs. 152/2006, for urban waste and for the special waste listed in Article 184(2) and (3)(g) of that decree. It also covers management of sewerage and purification plants.
It expressly excludes landfilling (conferimento in discarica) and incineration without efficient energy recovery. Those services are no longer in the 10% list and so fall to the 22% standard rate.
The same Budget Law made training for employment agencies taxable (record) and extended the 5% rate to mountaineering courses (record).
What it means
The rule is still in force. Waste operators must split their invoicing by activity. Other management services, storage and temporary deposit keep 10%. Landfill disposal and incineration without efficient energy recovery are charged at 22%. Municipalities usually cannot recover VAT on waste services, so the change raises the cost of disposal at the bottom of the waste hierarchy, which is the stated intent.
From 1 January 2027 the VAT Testo unico, D.Lgs. 10/2026, carries the same wording over as number 119 of Parte IV of its Tabella A (record). The scope does not change.
Proof
il numero 127-sexiesdecies) alla tabella A, parte III, del decreto del Presidente della Repubblica 26 ottobre 1972, n. 633, è sostituito dal seguente: «127-sexiesdecies) prestazioni di gestione, stoccaggio e deposito temporaneo, esclusi il conferimento in discarica e l'incenerimento senza recupero efficiente di energia, come definite dall'articolo 183, comma 1, lettere n), aa), bb), del decreto legislativo 3 aprile 2006, n. 152, di rifiuti urbani e di rifiuti speciali di cui all'articolo 184, commi 2 e 3, lettera g), del medesimo decreto legislativo, nonché prestazioni di gestione di impianti di fognatura e depurazione»number 127-sexiesdecies) of Table A, Part III, of Presidential Decree 26 October 1972, n. 633, is replaced by the following: "127-sexiesdecies) management, storage and temporary deposit services, excluding landfilling and incineration without efficient energy recovery, as defined by Article 183, paragraph 1, letters n), aa), bb), of Legislative Decree 3 April 2006, n. 152, for urban waste and for special waste under Article 184, paragraphs 2 and 3, letter g), of the same Legislative Decree, and management services for sewerage and purification plants"
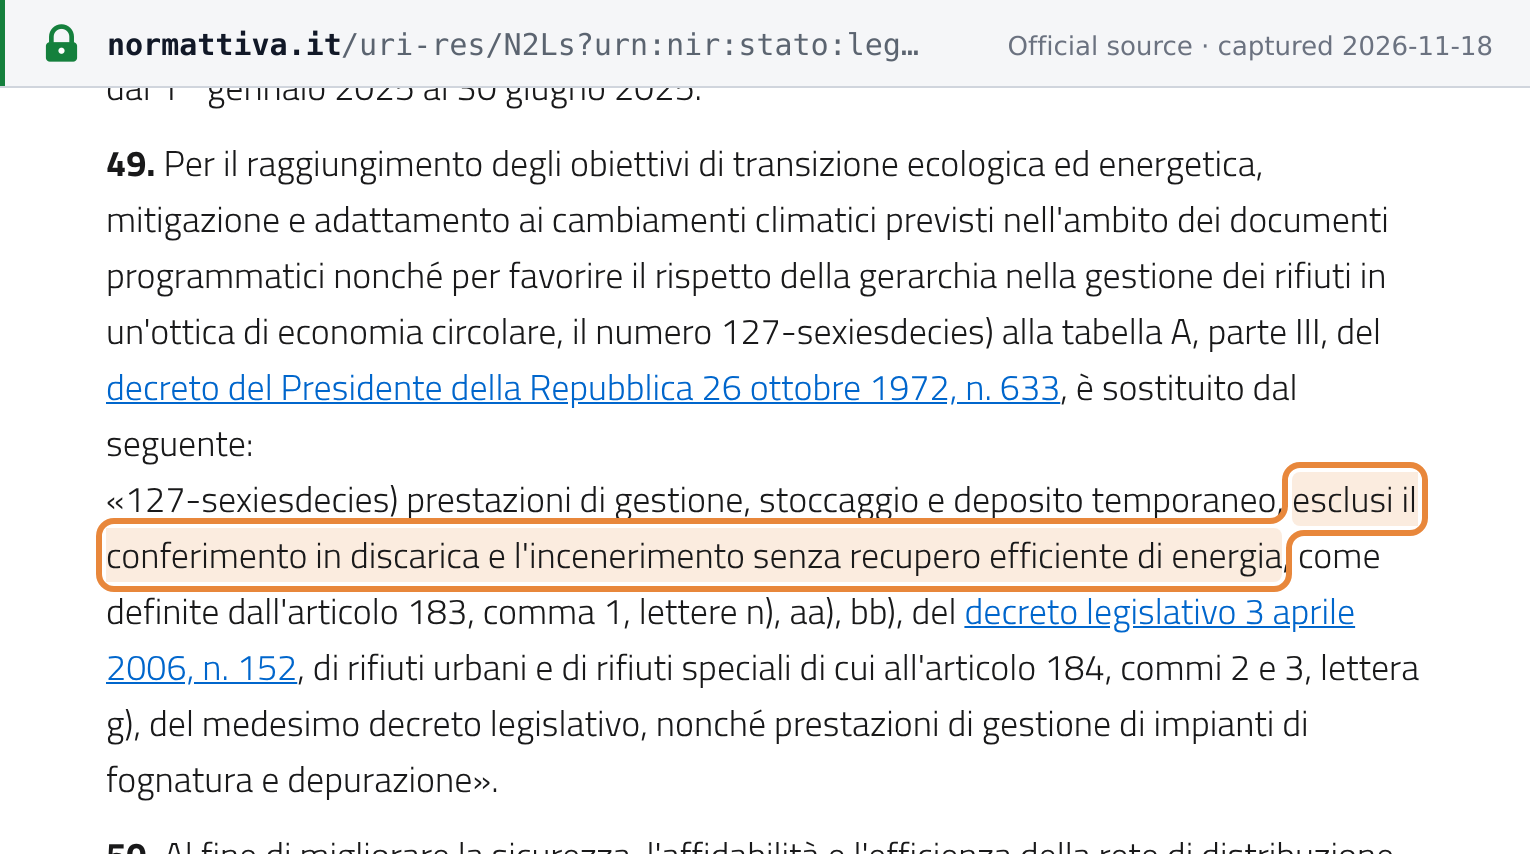 Source snapshot of the official page. Open full size ↗