Japan removes the small-business JCT exemption for three years after ¥2 million of gold or platinum bullion purchases
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- JCT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 30 March 2024
- Effective
- 1 April 2024
- Instrument
- JP-ACT--6-8
- Authority
- 国会 (National Diet of Japan)
- Verified
- Fetched from official source · high confidence
Businesses not using the simplified method that buy or import gold or platinum bullion and similar assets totalling ¥2 million or more (tax-exclusive) in a tax period.
No action — in force since 1 April 2024. A business that buys ¥2 million or more (tax-exclusive) of gold or platinum bullion in a non-simplified tax period loses the small-business exemption, and cannot elect the simplified method, through the period that includes the third anniversary.
令和6年法律第8号 (FY2024 Tax Reform Act, promulgated 30 March 2024, in force 1 April 2024) inserted Consumption Tax Act Article 12-4(3): a business that, in a tax period not under the simplified method, purchases gold or platinum bullion or similar assets (金地金等) totalling ¥2 million or more tax-exclusive (threshold set by CT Enforcement Order Article 25-5(4), 令和6年政令第145号) cannot use the small-business exemption from the next tax period through the period that includes the third anniversary of that period's first day. Article 37(4) bars electing the simplified method for the same span. It applies to bullion purchases made on or after 1 April 2024.
What changed in detail
The FY2024 tax reform act, 所得税法等の一部を改正する法律 (令和6年法律第8号), promulgated on 30 March 2024 and in force on 1 April 2024, inserted Consumption Tax Act Art. 12-4(3).
It applies to a business that, in a tax period in which it does not use the simplified method under Art. 37(1), buys gold or platinum bullion or similar assets specified by Ministry of Finance ordinance (金地金等) in Japan, or imports them. Where the total of those purchases in the period is a “high amount”, the small-business exemption under Art. 9(1) does not apply from the next tax period through the tax period that includes the third anniversary of the first day of the purchase period.
The Act left the threshold to Cabinet Order. CT Enforcement Order Art. 25-5(4), as amended by 令和6年政令第145号, sets it at ¥2 million or more, tax-exclusive. The same Act inserted Art. 37(4), which bars electing the simplified method for the same span. Supplementary Art. 13(4) applies the rule to bullion purchases made on or after 1 April 2024.
What it means
The rule is still in force; the current consolidated text of Art. 12-4(3) has not changed. A business that bought ¥2 million or more of bullion in a period from April 2024 onward stays taxable, and outside the simplified method, until the period that includes the third anniversary. The earliest of those lock-ins therefore run into 2027.
Credit on bullion is now paired with a minimum taxable period, so a business cannot claim it and then fall back into the exemption straight away. Businesses that hold bullion as an investment or as stock should track their purchases per tax period against the ¥2 million figure.
Proof
第三十七条第一項の規定の適用を受けない課税期間中に国内における金若しくは白金の地金その他これに類する資産として財務省令で定める資産(以下この項において「金地金等」という。)の課税仕入れ又は金地金等に該当する課税貨物の保税地域からの引取りDomestic taxable purchases, during a tax period in which Article 37(1) does not apply, of gold or platinum bullion or other similar assets specified by Ministry of Finance ordinance (referred to in this paragraph as "gold bullion etc."), or the removal from a bonded area of taxable goods that are gold bullion etc.
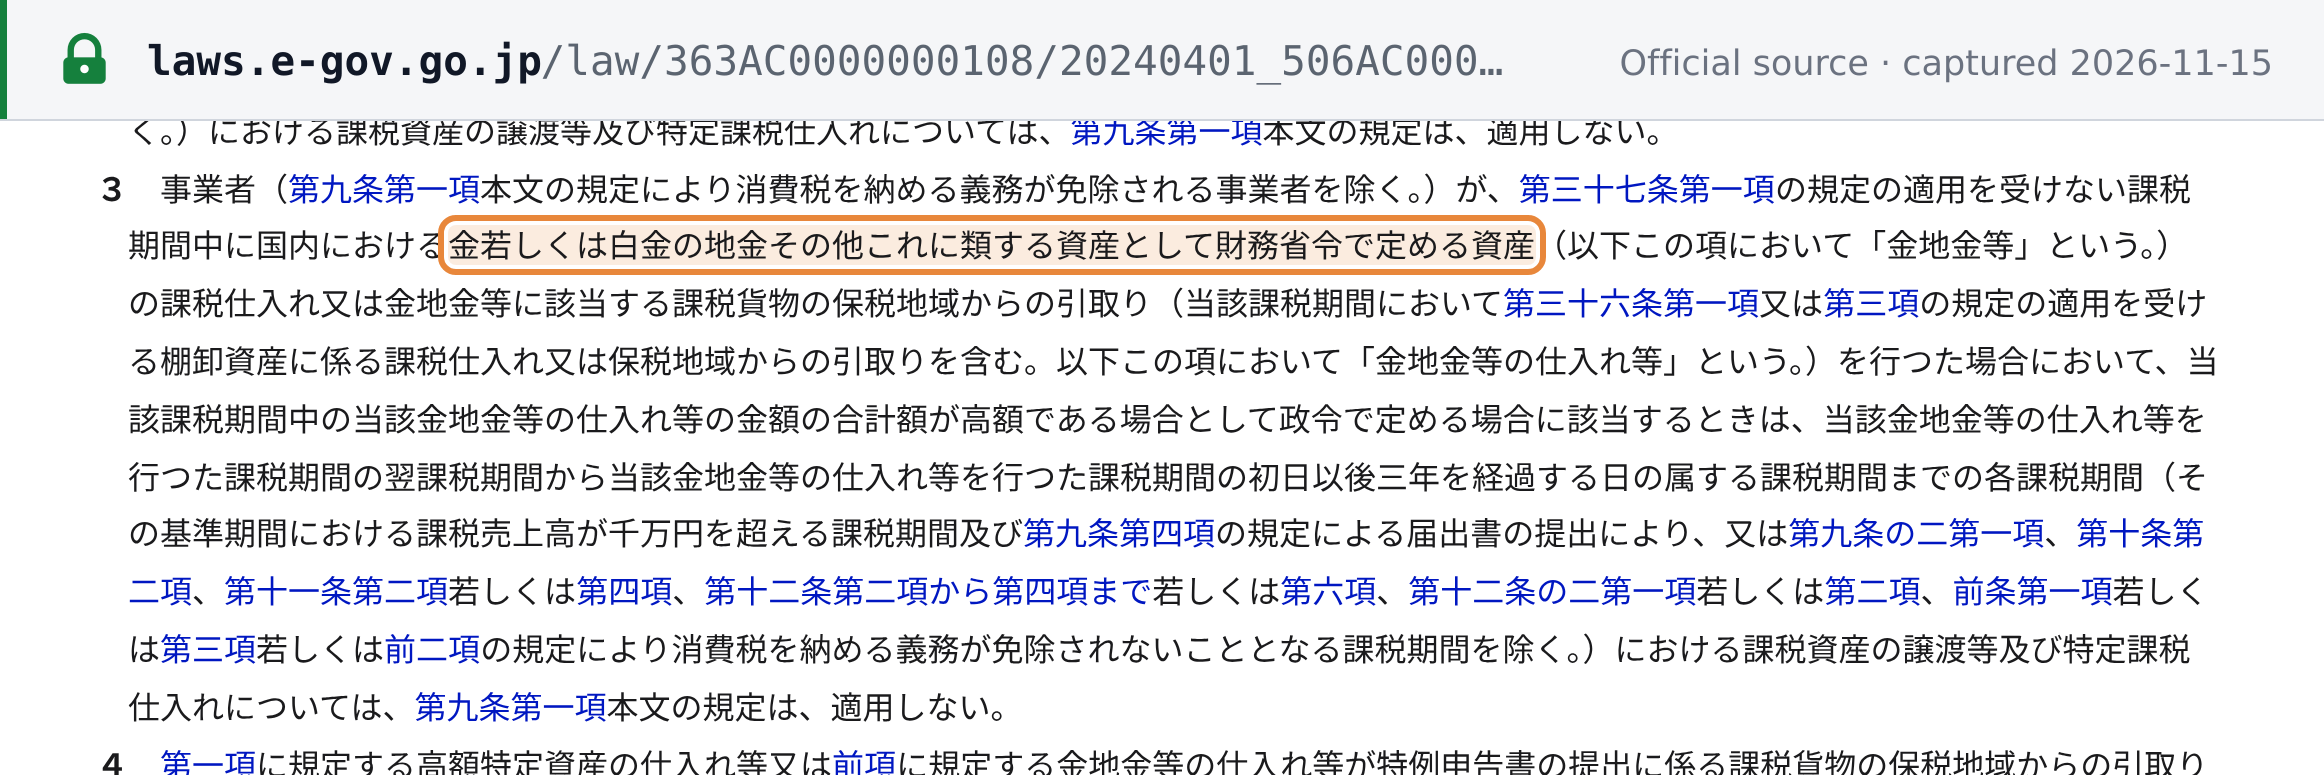 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 消費税法(昭和六十三年法律第百八号), e-Gov law revision 363AC0000000108_20240401_506AC0000000008 (as amended by 令和六年法律第八号, in force 2024-04-01), Art. 12-4(3) · laws.e-gov.go.jp