Kenya moves fertilizers and agricultural pest control products from zero-rated to VAT-exempt
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 13 December 2024
- Effective
- 27 December 2024
- Authority
- National Council for Law Reporting (Kenya Law)
- Verified
- Fetched from official source · high confidence
Manufacturers and suppliers of fertilizers, agricultural pest control products and their inputs in Kenya.
No action — monitoring only.
Tax Laws (Amendment) Act 2024 (Act No. 12 of 2024, in force 27 December 2024), s.22, deletes paragraphs 16, 19, 24 and 25 of Part A of the VAT Act Second Schedule (zero-rated): inputs for agricultural pest control products, agricultural pest control products, fertilizers of Chapter 31, and fertilizer inputs. The same goods are moved to the First Schedule (exempt, new paras 149-152), so suppliers lose the right to recover input VAT on them.
What changed in detail
Section 22 of the Tax Laws (Amendment) Act, 2024 (No. 12 of 2024, Kenya Gazette Supplement No. 215 of 13 December 2024; commenced 27 December 2024) amends Part A of the Second Schedule (zero-rated supplies) to the VAT Act, CAP 476, by deleting four paragraphs:
- paragraph 16, inputs for agricultural pest control products;
- paragraph 19, agricultural pest control products;
- paragraph 24, fertilizers of Chapter 31;
- paragraph 25, fertilizer inputs.
The same goods are inserted into Part I of the First Schedule (exempt supplies) as new paragraphs 149 to 152 by section 21 of the Act (ke-vat-tlaa-2024-first-schedule). From 27 December 2024 their supply is exempt rather than zero-rated.
What it means
Exempt and zero-rated both mean no VAT on the sale, so the change is invisible on the invoice to a farmer. It is not invisible to the supplier: zero-rating allows input VAT on costs to be recovered, exemption does not. Fertilizer and pest-control manufacturers and distributors lost that recovery from 27 December 2024, and input VAT they incur is now a cost that tends to work its way into prices. Nothing in the frozen record shows this reversed; treat the exempt status as the position unless a later change says otherwise.
Proof
by deleting paragraph 25.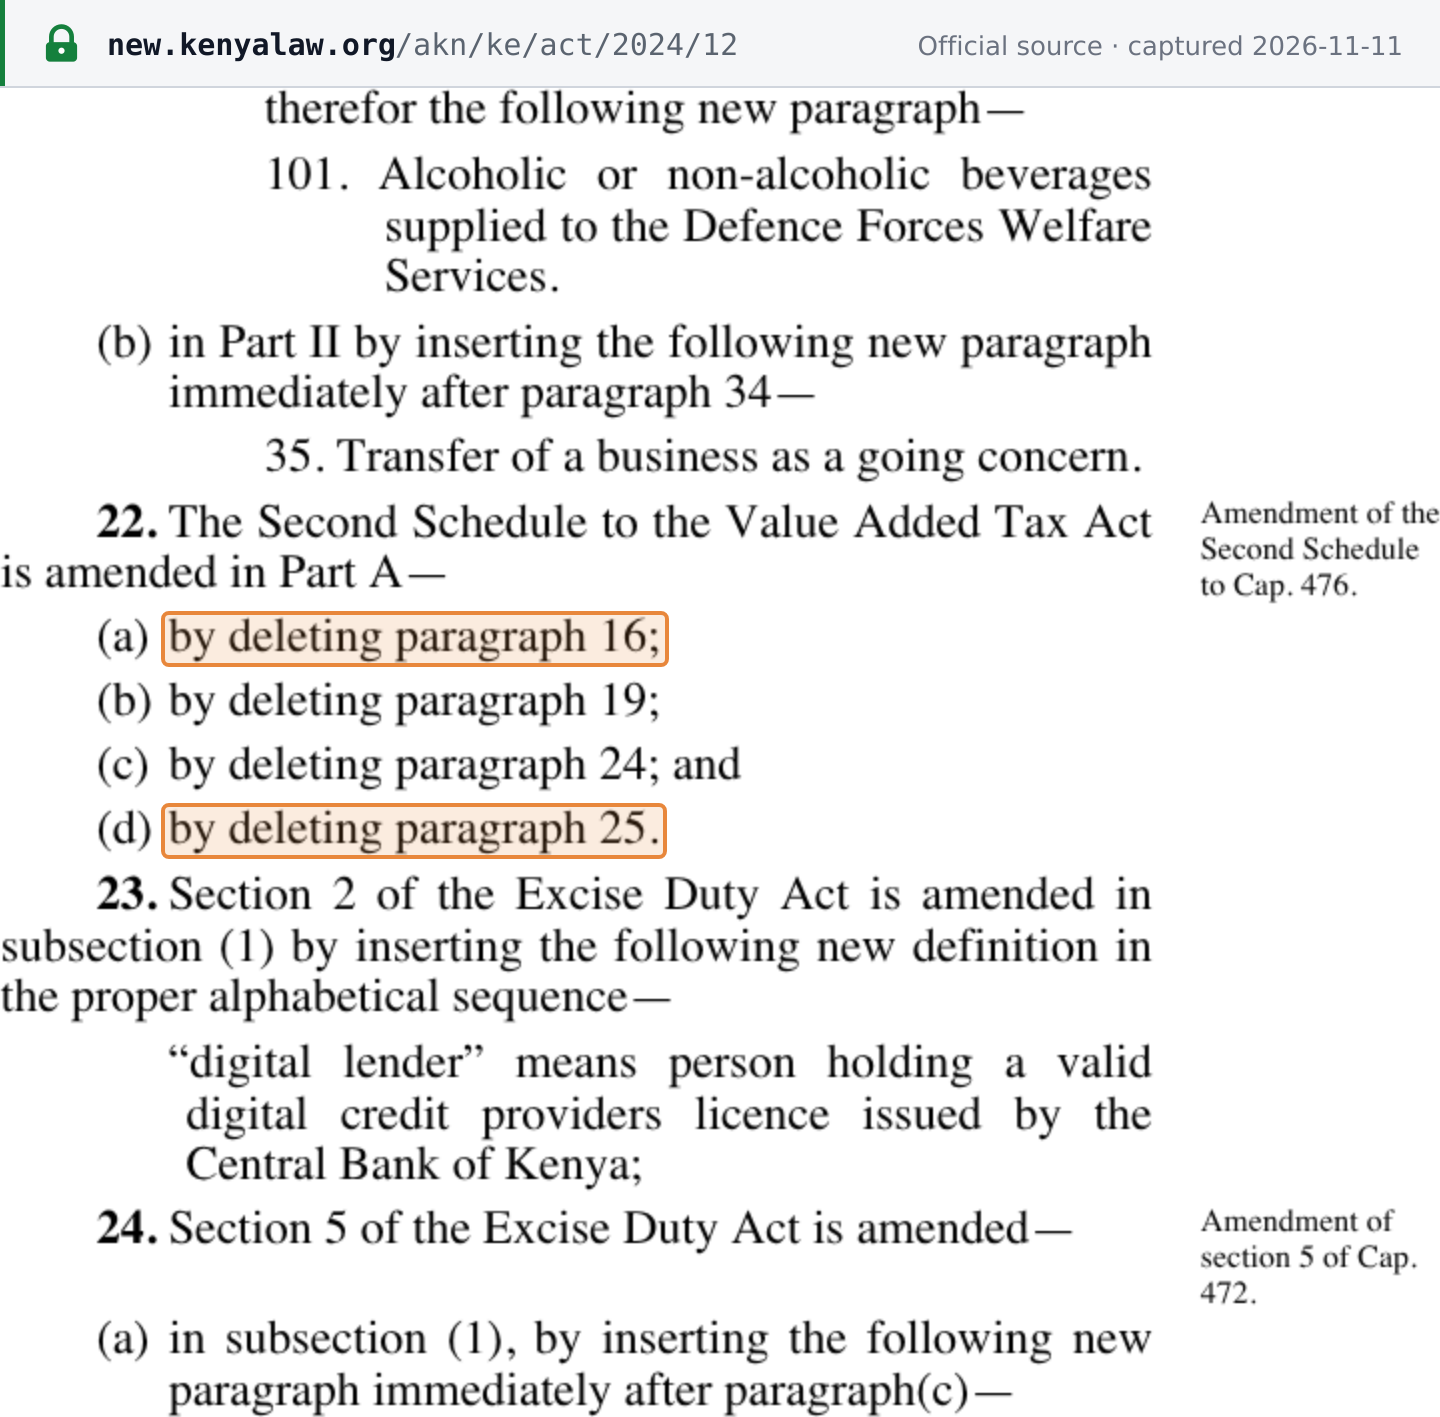 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Tax Laws (Amendment) Act, 2024 (No. 12 of 2024), Kenya Gazette Supplement No. 215, 13 December 2024 · kenyalaw.org