Mexico requires digital service providers to give the SAT permanent real-time access to their systems from April 2026
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 7 November 2025
- Effective
- 1 April 2026
- Instrument
- MX-DECRETO-Decreto-CFF-07-11-2025
- Authority
- Diario Oficial de la Federación (DOF)
- Verified
- Fetched from official source · high confidence
Resident and non-resident providers of digital services to recipients in Mexico under articles 1o.-A BIS and 18-B of the IVA law, including intermediation platforms.
Digital service providers (LIVA articles 1o.-A BIS and 18-B) must give the SAT permanent, real-time online access to the compliance information in their systems from 1 April 2026, in the terms of RMF rule 2.9.21. Failure can lead to temporary blocking of the service in Mexico.
New article 30-B of the Código Fiscal de la Federación, added by the reform decree published in the DOF on 7 November 2025 (evening edition) and in force from 1 April 2026, requires providers of digital services under LIVA articles 1o.-A BIS and 18-B to give the tax authorities permanent, real-time online access to the information in their systems that shows compliance with their tax obligations, in the terms the SAT sets by general rules. Non-compliance can lead to temporary blocking of access to the service under LIVA articles 18-H BIS to 18-H QUINTUS.
What changed in detail
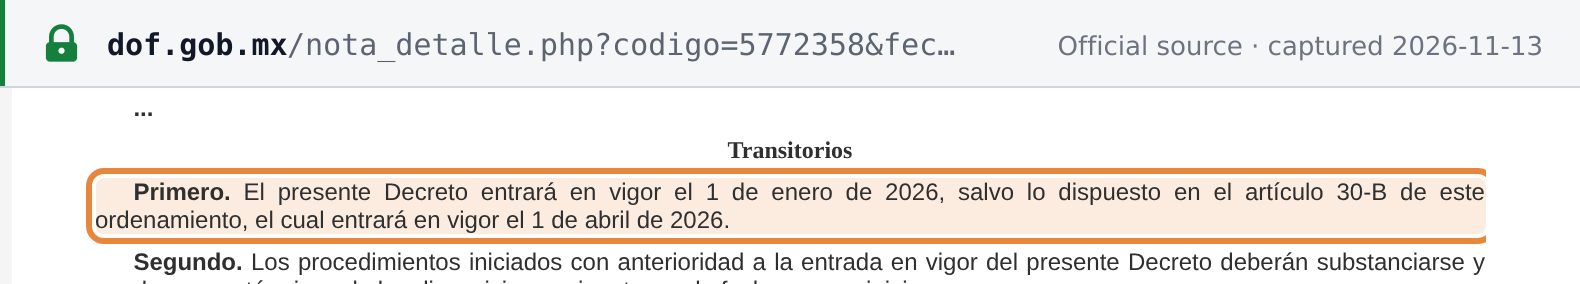
The Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, published in the Diario Oficial de la Federación on 7 November 2025 (evening edition), adds a new article 30-B to the Código Fiscal de la Federación (CFF). The decree as a whole entered into force on 1 January 2026, but its first transitional article puts article 30-B in force on 1 April 2026.
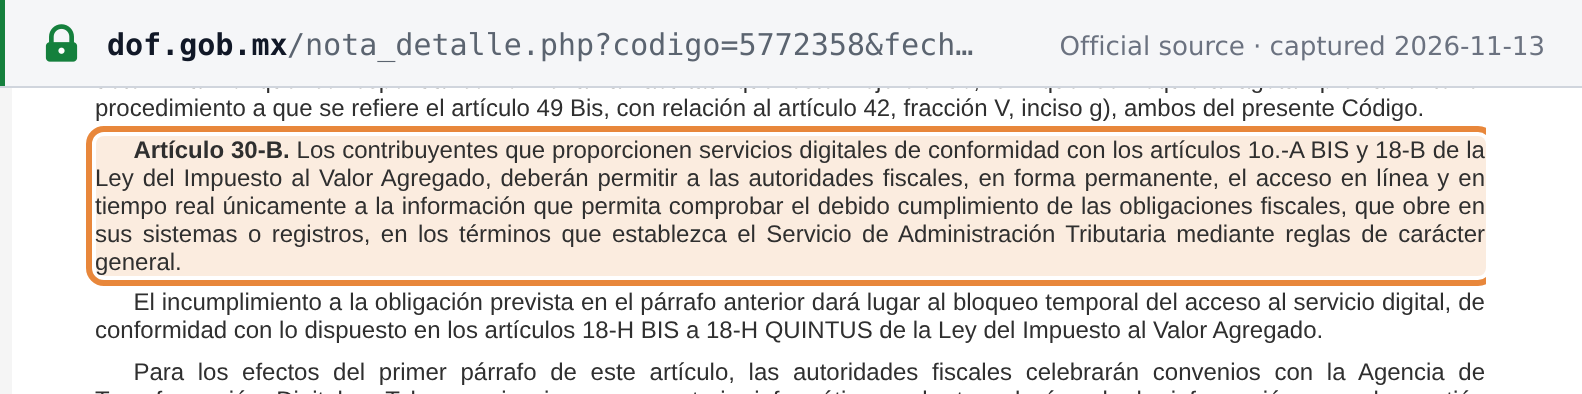
Article 30-B applies to taxpayers that provide digital services under articles 1o.-A BIS and 18-B of the IVA law: non-resident and resident providers of digital services to recipients in Mexico, including intermediation platforms. They must give the tax authorities permanent, online, real-time access solely to the information in their systems or records that shows due compliance with their tax obligations, in the terms the SAT sets by general rules.
Failure to comply leads to temporary blocking of access to the digital service in Mexico under articles 18-H BIS to 18-H QUINTUS of the IVA law. For the access itself, the tax authorities are to sign agreements with the Agencia de Transformación Digital y Telecomunicaciones on technology management and data analysis.
The same decree also introduced the false-CFDI regime; see Mexico defines false CFDIs and adds express audits.
What it means
Article 30-B is the statutory basis; the operating detail is in RMF 2026 rule 2.9.21, which lists the data fields, requires next-day loading and five-year retention, and set a 30 April 2026 deadline for giving the SAT access credentials. See Mexico requires digital service platforms to give the SAT online access.
The obligation has been in force since 1 April 2026 and remains so in November 2026. The sanction is the point: a foreign platform that does not provide access risks having its service blocked in Mexico, not just a fine.
Proof
Primero. El presente Decreto entrará en vigor el 1 de enero de 2026, salvo lo dispuesto en el artículo 30-B de este ordenamiento, el cual entrará en vigor el 1 de abril de 2026.First. This Decree enters into force on 1 January 2026, except article 30-B, which enters into force on 1 April 2026.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, DOF 7 de noviembre de 2025, Edición Vespertina (Cámara de Diputados reform file CFF_ref62_07nov25) · www.diputados.gob.mx
deberán permitir a las autoridades fiscales, en forma permanente, el acceso en línea y en tiempo real únicamente a la información que permita comprobar el debido cumplimiento de las obligaciones fiscalesmust allow the tax authorities, permanently, online and real-time access solely to the information that makes it possible to verify due compliance with tax obligations
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, DOF 7 de noviembre de 2025, Edición Vespertina (Cámara de Diputados reform file CFF_ref62_07nov25) · www.diputados.gob.mx