Mexico defines false CFDIs, adds express audits and makes trading in them a crime from 2026
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Invoice rules
- Status
- In force
- Impact
- Action required
- Announced
- 7 November 2025
- Effective
- 1 January 2026
- Instrument
- MX-DECRETO-Decreto-CFF-07-11-2025
- Authority
- Diario Oficial de la Federación (DOF)
- Verified
- Fetched from official source · high confidence
All CFDI issuers and recipients in Mexico, and digital platforms that carry advertising for invoices.
Taxpayers that issue or use CFDIs for simulated or non-existent operations face new statutory sanctions: temporary CSD (certificate) restriction under expanded CFF article 17-H Bis, targeted express verification visits under new article 49 Bis, publication in the SAT's list of presumed false CFDI issuers (giving counterparties 30 days to self-correct), and criminal penalties under new article 113 Bis. Digital platforms that allow advertising for sham invoices also face criminal liability.
The decree reforming the Código Fiscal de la Federación published in the DOF on 7 November 2025 (evening edition), in force from 1 January 2026, adds a requirement that every CFDI cover real, existing operations (new article 29-A, fraction IX); CFDIs that do not are false. New article 49 Bis creates an express audit visit, of at most 24 business days, during which the issuer's CFDI issuance is suspended. Issuers found to have issued false CFDIs are published on the SAT portal and in the DOF. Recipients then have 30 calendar days to reverse the tax effect or have their digital seal certificate restricted (new article 17-H Bis, fraction XIV). Article 113 Bis is amended to punish anyone who issues, sells, buys, acquires or gives tax effect to false CFDIs, and digital platforms that allow adverts for them.
What changed in detail
The Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, published in the Diario Oficial de la Federación on 7 November 2025 (evening edition), entered into force on 1 January 2026. It builds a regime against false invoices (CFDIs):
- Article 29-A, fraction IX (new): every CFDI must cover existing, true operations or real legal acts. A CFDI that does not is false for the purposes of the CFF. New article 29-A Bis lets the authority act on this in any audit without first running the express procedure.
- Article 49 Bis (new): an express home visit, ordered under new article 42, fraction V, subsection g), when the authority presumes an issuer’s CFDIs are false. The order suspends the issuer’s CFDI issuance. The taxpayer has five business days to bring evidence, the authority fifteen to decide, and the procedure may last at most 24 business days.
- If the presumption stands, the CFDIs are false with general effect. The issuer’s name and RFC are published on the SAT portal and in the DOF within 45 business days, and recipients have 30 calendar days from the DOF publication to reverse the tax effect by amended return. Otherwise their digital seal certificate is restricted under new article 17-H Bis, fraction XIV.
- Article 113 Bis (amended): punishes anyone who issues, sells, buys, acquires or gives tax effect to false CFDIs, and digital platforms, and their owners, that allow adverts for buying or selling them.
Procedures started before 2026 continue under the old rules.
What it means
Before this reform, simulated-invoice cases ran through the slower article 69-B list procedure. The express visit now lets the SAT stop an issuer invoicing within days and, within about three and a half months (24 business days for the visit plus up to 45 business days for publication), put every customer on a 30-day clock to undo the deduction or credit.
The regime is in force in November 2026. For recipients the practical risk is counterparty risk: check the DOF and SAT publications for suppliers named under article 49 Bis. Missing the 30-day window costs the ability to issue CFDIs, not only the IVA credit. Article 30-B, from the same decree, covers digital platforms’ data access.
Proof
expida, enajene, compre, adquiera o dé efectos fiscales a comprobantes fiscales falsosissues, sells, buys, acquires or gives tax effect to false tax receipts
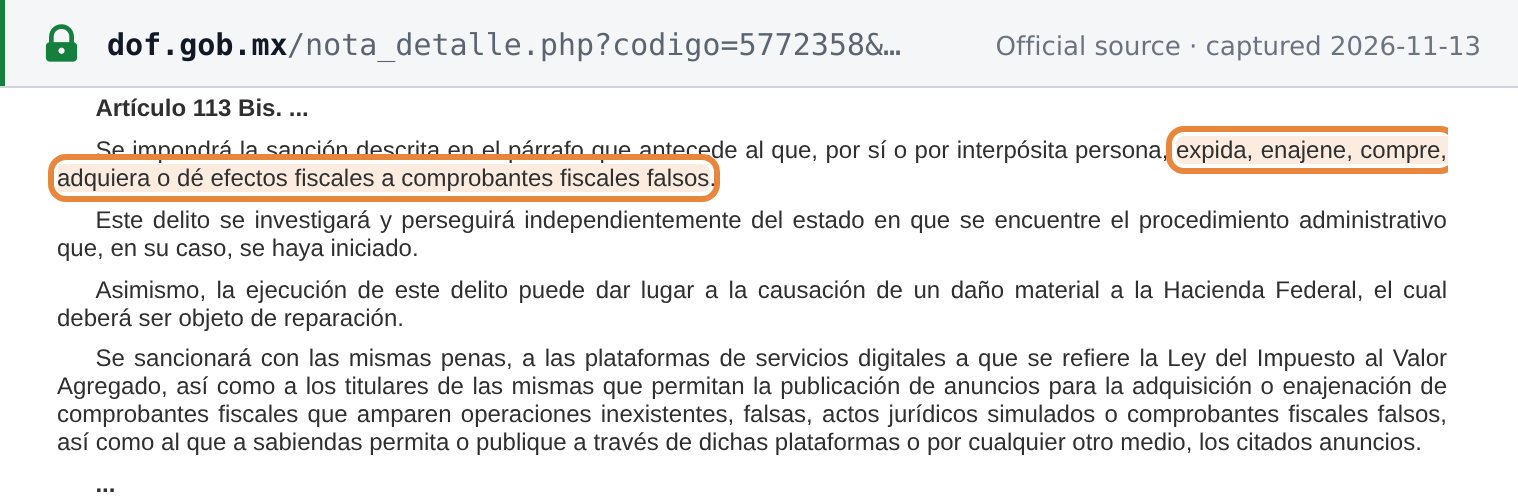 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, DOF 7 de noviembre de 2025, Edición Vespertina (Cámara de Diputados reform file CFF_ref62_07nov25) · www.diputados.gob.mx
Amparar operaciones existentes, verdaderas o actos jurídicos reales.Cover existing, true operations or real legal acts.
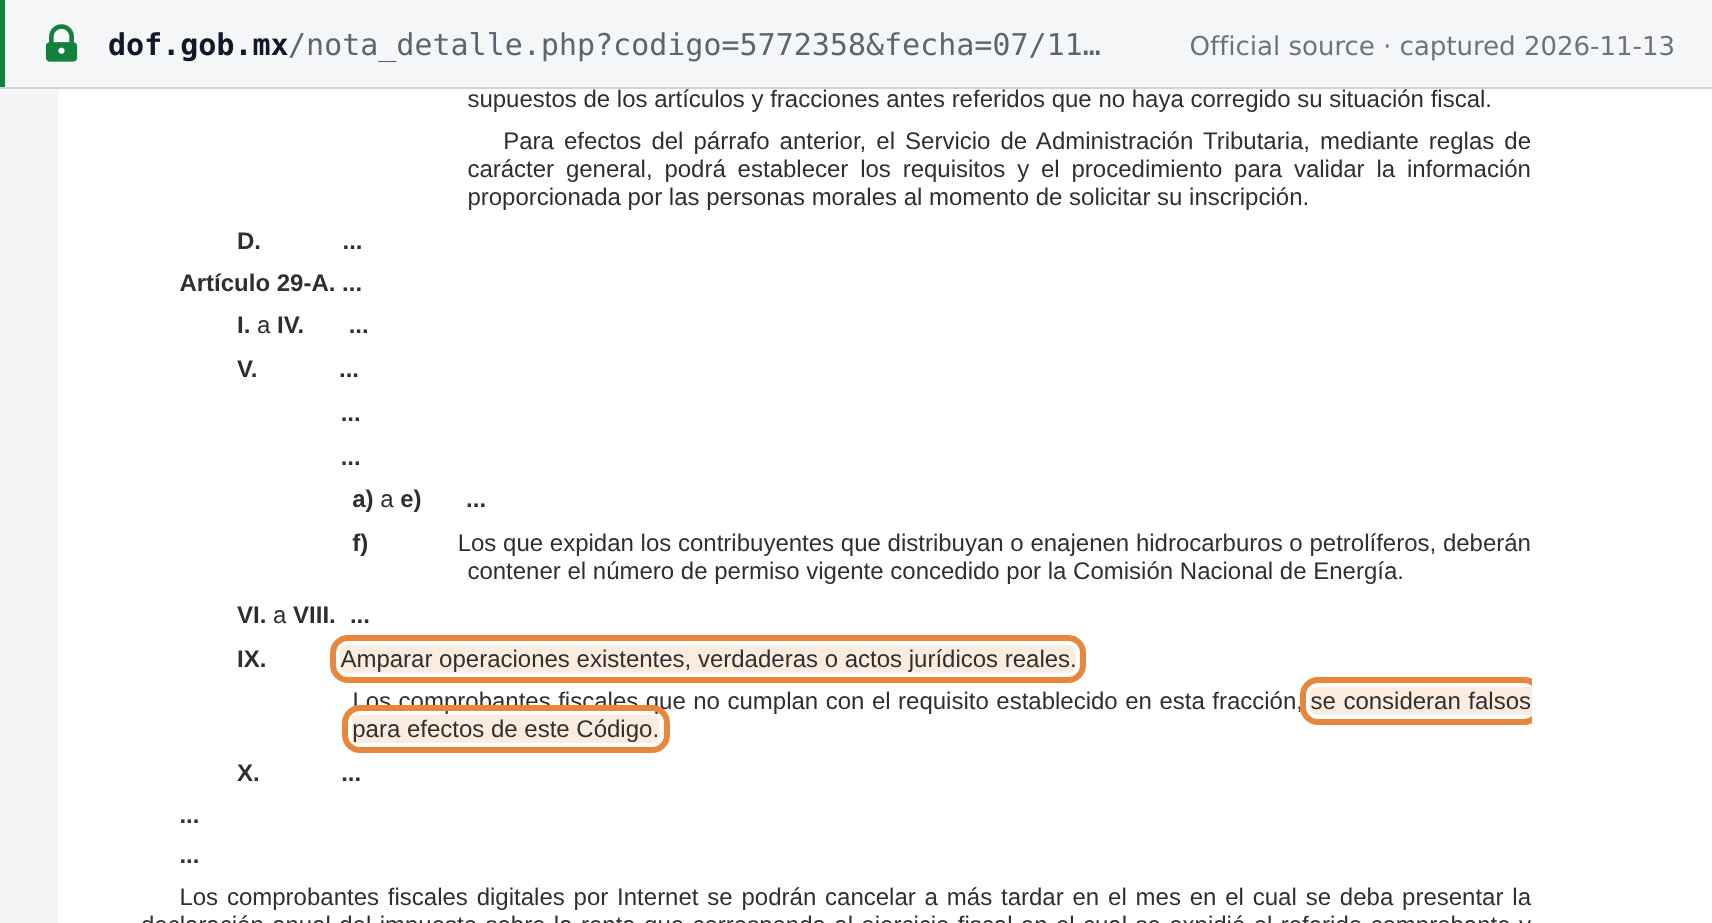 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Decreto por el que se reforman, adicionan y derogan diversas disposiciones del Código Fiscal de la Federación, DOF 7 de noviembre de 2025, Edición Vespertina (Cámara de Diputados reform file CFF_ref62_07nov25) · www.diputados.gob.mx