Mexico makes crowdfunding platforms withhold the IVA on interest companies pay to individuals
This page records one dated change. For the rules in Mexico as they stand today, see the Mexico guide →
- Jurisdiction
- Mexico
- Tax
- IVA
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 11 October 2024
- Effective
- 12 October 2024
- Instrument
- MX-RESOLUCION-MISCELANEA-2a-RM-RMF-2024
- Authority
- Servicio de Administración Tributaria (SAT)
- Verified
- Fetched from official source · high confidence
Crowdfunding institutions (Instituciones de Financiamiento Colectivo) authorised under the Fintech law, and companies paying interest to individual lenders through them.
No action — monitoring only. Rule 4.1.12 applied from 12 October 2024 to 31 December 2025; from 1 January 2026 crowdfunding IVA withholding is governed by Ley de Ingresos 2026 art. 25, fracción VIII.
New rule 4.1.12 of the Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024 (DOF 11 October 2024, in force 12 October 2024) made crowdfunding institutions (Instituciones de Financiamiento Colectivo) withhold and remit IVA, in place of the company, on interest that companies pay to individuals through the platform, applying the general rate to nominal accrued interest and also meeting the information obligations of LIVA article 32, fractions V and VI. The withheld IVA is creditable for the paying company under LIVA article 5o., fraction IV. The rule was not carried into the RMF for 2026.
What changed in detail
The Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024, published in the Diario Oficial de la Federación on 11 October 2024, added rule 4.1.12. The resolution entered into force the day after publication, 12 October 2024.
Under article 1o.-A, fraction II, subsection a) of the IVA law, a company (persona moral) that pays interest to an individual must withhold the IVA on it. Rule 4.1.12 moves that duty to the platform when the loan runs through a crowdfunding institution (Institución de Financiamiento Colectivo) regulated by the Fintech law: the institution replaces the company in withholding and remitting the IVA, and in the related information obligations of article 32, fractions V and VI of the IVA law.
The withholding is made at the general IVA rate set in article 1o. of the IVA law, on the nominal value of the accrued interest. The IVA withheld by the platform is creditable for the paying company under article 5o., fraction IV of the IVA law, provided the other requirements are met.
The rule was framed as a facility (facilidad) and covered only interest paid by companies to individuals. It was carried into the RMF for 2025.
What it means
The rule is spent. It applied from 12 October 2024 to 31 December 2025 and was not carried into the RMF for 2026. From 1 January 2026, article 25, fraction VIII of the Ley de Ingresos de la Federación 2026 puts crowdfunding IVA withholding in statute and widens it: the platform withholds 16% on interest paid to any recipient, remits by the 17th of the following month and issues withholding CFDIs. See Mexico’s 2026 revenue law makes crowdfunding platforms withhold IVA on all interest, which supersedes this record.
For periods up to the end of 2025, companies that borrowed through a platform can rely on the platform’s withholding instead of their own.
Proof
Para los efectos del artículo 1o.-A, fracción II, inciso a) de la Ley del IVA, las Instituciones de Financiamiento Colectivo a que se refiere la Ley para Regular las Instituciones de Tecnología Financiera, a través de las que se realicen operaciones de financiamiento en las cuales personas morales paguen intereses a personas físicas, sustituirán a las personas morales en el cumplimiento de las obligaciones de retener y enterar el IVAFor the purposes of article 1o.-A, fraction II, subsection a) of the IVA Law, crowdfunding institutions under the Law to Regulate Financial Technology Institutions, through which financing operations are carried out in which legal entities pay interest to individuals, shall replace the legal entities in fulfilling the obligations to withhold and remit IVA
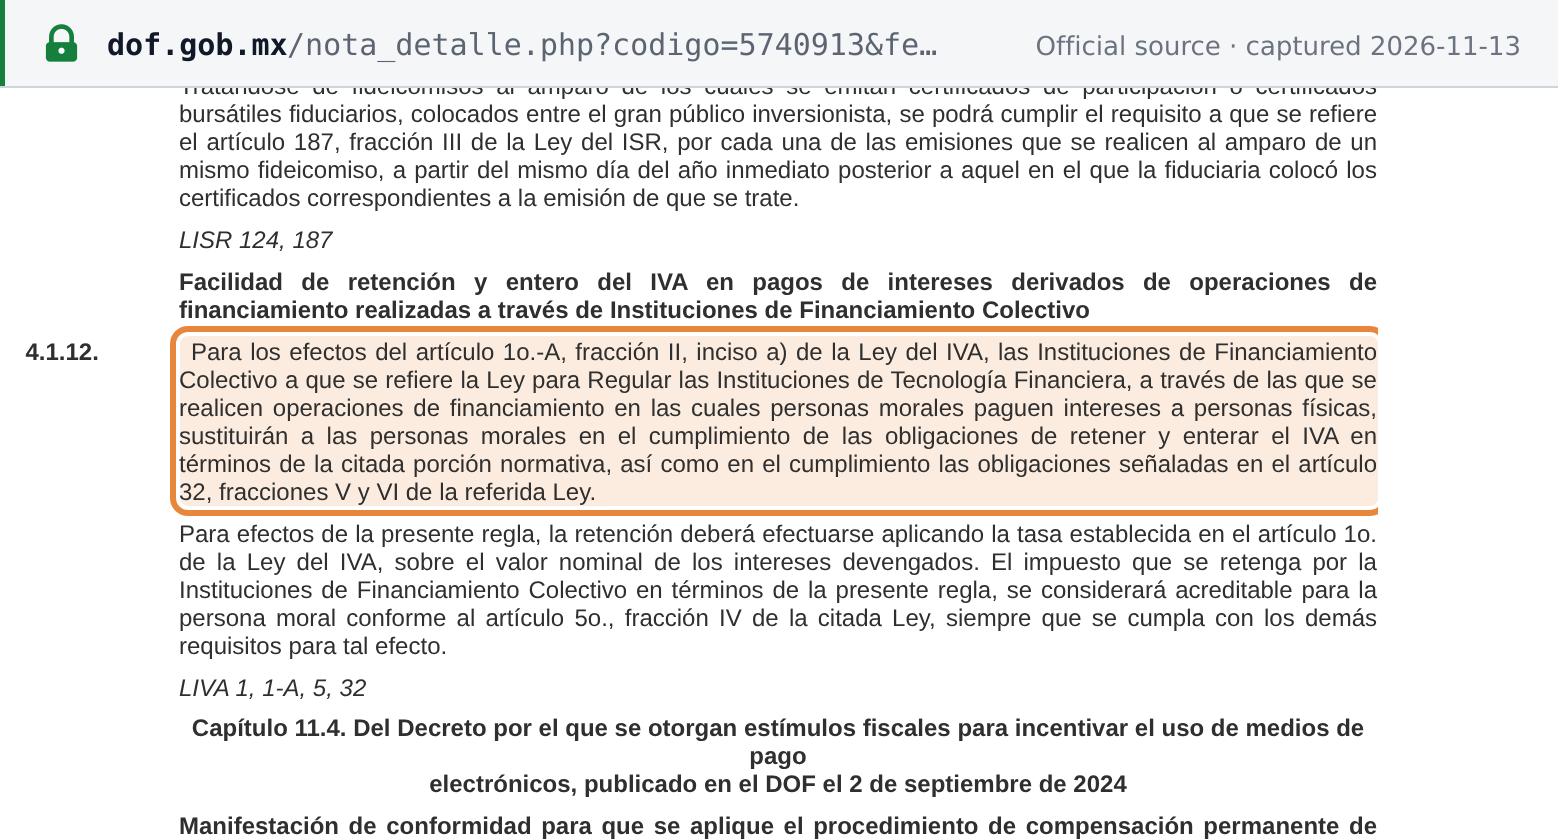 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Segunda Resolución de Modificaciones a la Resolución Miscelánea Fiscal para 2024, DOF 11 de octubre de 2024 (SAT edition) · www.sat.gob.mx