BIR gives non-resident digital service providers until 1 June 2025 to register for VAT (RR No. 14-2025)
This page records one dated change. For the rules in Philippines as they stand today, see the Philippines guide →
- Jurisdiction
- Philippines
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 25 April 2025
- Effective
- 2 April 2025
- Instrument
- PH-REVENUE-REGULATIONS-RR-14-2025
- Authority
- Bureau of Internal Revenue (BIR), Philippines
- Verified
- Fetched from official source · high confidence
Non-resident digital service providers required to register for Philippine VAT on digital services under RA 12023 and RR No. 3-2025.
No action — monitoring only. The registration deadline (1 June 2025) and the VAT start date (2 June 2025) have passed.
BIR Revenue Regulations No. 14-2025, issued 25 April 2025, amends the transitory provision of RR 3-2025 (VAT on digital services under RA 12023). Non-resident digital service providers now have 120 days from RR 3-2025's effectivity, until 1 June 2025, to register through the VDS portal, and are subject to VAT from 2 June 2025. Previously registration was due within 60 days. Under Section 4 the regulations took effect on 2 April 2025 or on publication, whichever is earlier.
What changed in detail
Revenue Regulations No. 14-2025, issued on 25 April 2025, amend Section 14 (Transitory Provision) of RR No. 3-2025. That regulation implements the VAT on digital services under RA 12023.
- Registration window: non-resident digital service providers (NRDSPs) must register, or update their registration, within 120 days of RR 3-2025 taking effect. Before the amendment the window was 60 days.
- Channel: registration goes through the VAT on Digital Services (VDS) Portal or the BIR’s Online Registration and Update System (ORUS).
- Dates: NRDSPs have until 1 June 2025 to register and are subject to VAT from 2 June 2025.
- Further extension: the Commissioner of Internal Revenue may extend the transition deadlines again if necessary.
The header of the full text is dated 2 April 2025 and the BIR records stamp reads 25 April 2025. Section 4 makes the regulations effective on 2 April 2025 or on publication in the Official Gazette or on the BIR website, whichever is earlier.
What it means
The deadline is spent. Registration closed on 1 June 2025, and non-resident providers have charged Philippine VAT on B2B and B2C digital services since 2 June 2025. A provider entering the market now registers before its first supply and is liable straight away.
The amendment matters mostly for history: it aligned registration with the VAT start, so providers did not have to register two months before they owed anything. The substantive rules remain those in RR No. 3-2025. In June 2026, RMC No. 59-2026 clarified that non-resident providers must register and file even where their supplies are VAT-exempt.
Proof
All Non-Resident Digital Service Providers (NRDSPs) required to register under Section 5. of these Regulations shall register or update with the BIR within one hundred twenty (120) days from the effectivity of these Regulations through the VDS Portal or Online Registration and Update System (https://orus.bir.gov.ph/home) and shall immediately be subject to VAT after 120 days from the effectivity of these Regulations. Hence, NRDSPs are given until June 1, 2025 within which to register and shall be subject to VAT starting June 2, 2025.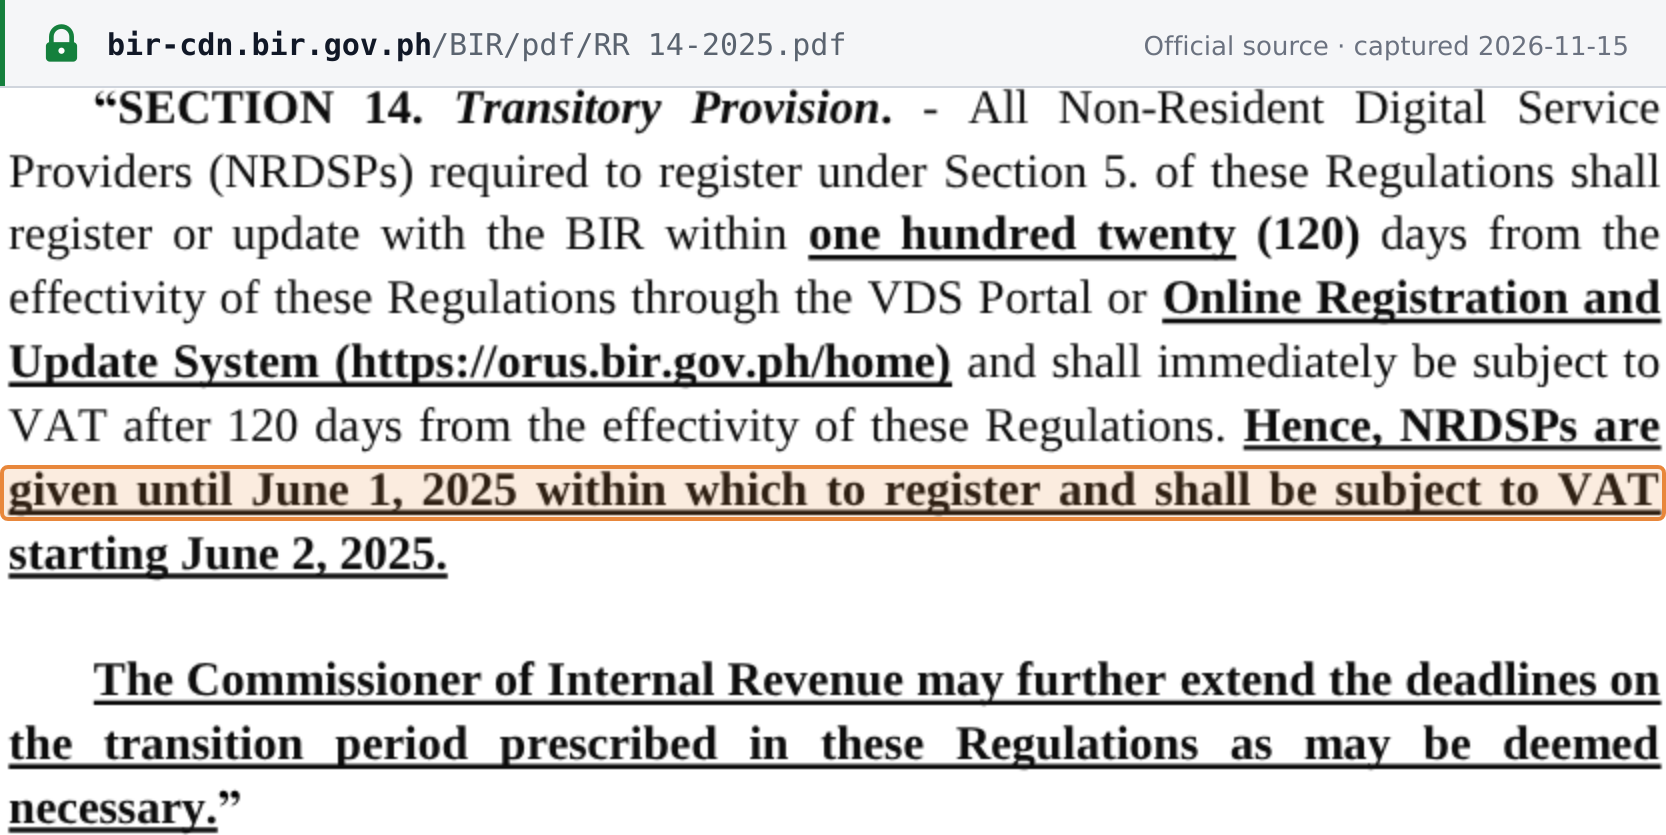 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Revenue Regulations No. 14-2025, Bureau of Internal Revenue digest, issued 25 April 2025, amended Sec. 14 of RR No. 3-2025 (p. 1) · bir-cdn.bir.gov.ph