BIR makes buyers remit 12% VAT on local purchases from ecozone and BOI-registered enterprises (RR No. 9-2025)
This page records one dated change. For the rules in Philippines as they stand today, see the Philippines guide →
- Jurisdiction
- Philippines
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- Action required
- Announced
- 27 February 2025
- Instrument
- PH-REVENUE-REGULATIONS-RR-9-2025
- Authority
- Bureau of Internal Revenue (BIR), Philippines
- Verified
- Fetched from official source · medium confidence
Registered Business Enterprises (ecozone, freeport and BOI-registered) selling locally, and Philippine businesses and government agencies that buy goods or services from them.
Buyers of goods or services from RBEs must self-remit 'VAT on Local Sales' (Form 0605 per transaction for ecozone goods, Form 1600-VT monthly otherwise) and may claim input VAT only after payment. RBEs must show 'VAT on Local Sales' on invoices; the system reconfiguration deadline is 31 December 2026 under RR 1-2026.
BIR Revenue Regulations No. 9-2025, issued 27 February 2025, takes effect 15 days after publication in the Official Gazette or on the BIR website, whichever comes first (Section 10). It implements Section 295(D) of the Tax Code as amended by RA 12066 (CREATE MORE). Local sales by Registered Business Enterprises are subject to 12% VAT whatever the RBE's income-tax incentive or location. In B2B sales the buyer pays and remits the VAT: per transaction on BIR Form 0605 before goods leave an ecozone or freeport, or monthly on Form 1600-VT by the 10th for services and BOI-registered sellers. In B2C sales the RBE remits. RBEs on the 5% GIE/SCIT regime may opt to register for VAT, with a three-year lock-in. Invoices must show 'VAT on Local Sales', with systems reconfigured by 31 December 2025, a deadline later extended by RR 1-2026.
What changed in detail
Revenue Regulations No. 9-2025, issued on 27 February 2025, implement Section 295(D) of the Tax Code as amended by Section 18 of the CREATE MORE Act (RA 12066).
- Scope: local sales of goods and services by Registered Business Enterprises (RBEs) bear 12% VAT unless exempt or zero-rated. The RBE’s income-tax regime (ITH, 5% GIE/SCIT, EDR or regular rate) and its location no longer matter.
- B2B (buyer remits): the RBE invoices the VAT as a separate line tagged “VAT on Local Sales”, and the buyer pays the price without it. The buyer pays the VAT to the BIR:
- goods from an ecozone or freeport: per transaction on BIR Form 0605, sent to the seller before the goods are released;
- services from an ecozone or freeport, and goods or services from BOI-registered enterprises: monthly on Form 1600-VT by the 10th of the following month, with Form 2307 to the seller.
- B2C (seller remits): an RBE on 5% GIE/SCIT remits on Form 0605 by the 10th of the following month. VAT-registered RBEs report the VAT in their quarterly return.
- Optional VAT registration: an RBE whose activities are all under 5% GIE/SCIT may register for VAT for its local sales. Under Section 236(G) it cannot cancel for three years.
- Input tax: buyers may claim input VAT only after paying it.
- Invoices: existing manual stock may be stamped “VAT on Local Sales”. System users had until 31 December 2025 to reconfigure.
The digest does not state an effective date; Section 10 of the full text provides that the regulations take effect 15 days after publication.
What it means
The regime is in force as amended. RR No. 1-2026 let buyers pay once for bulk shipments covered by several invoices, carved several sellers out of buyer remittance, and moved the system deadline to 31 December 2026.
In practice this is a reverse charge, and buyers carry the compliance work. An accounts-payable team that pays an RBE invoice without filing Form 0605 or 1600-VT has paid less than the full amount due and cannot claim the input VAT. It should identify its RBE suppliers and check each invoice for the “VAT on Local Sales” tag.
The ecozone DME election under RR No. 13-2023 came before this regime.
Proof
Local sales of goods and/or services by an RBE shall be subject to 12% Value-Added Tax (VAT), unless otherwise exempt or zero-rated under Titles IV and XIII of the Tax Code.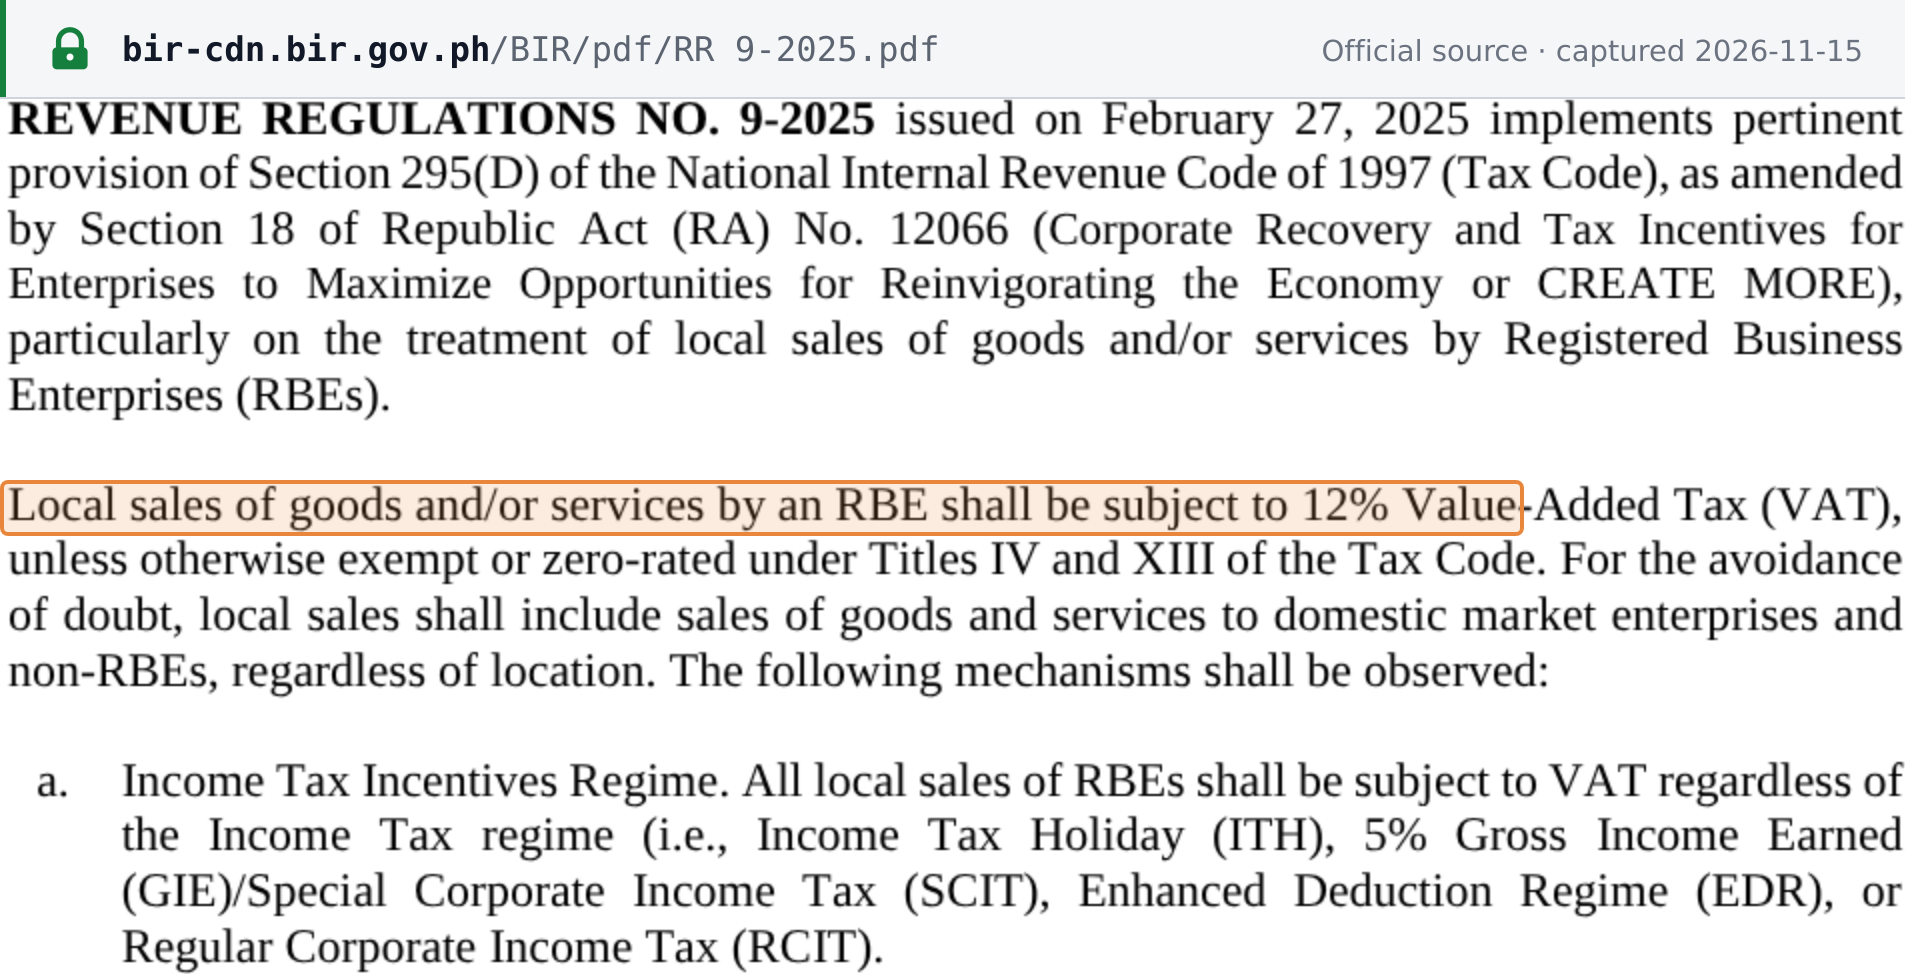 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Revenue Regulations No. 9-2025, Bureau of Internal Revenue digest, issued 27 February 2025 (p. 1) · bir-cdn.bir.gov.ph