Poland lets EU small businesses using its VAT exemption issue simplified invoices showing their EX number from 2025
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Invoice rules
- Status
- In force
- Impact
- FYI
- Announced
- 27 December 2024
- Effective
- 1 January 2025
- Instrument
- PL-MINISTERIAL-REGULATION-DU-2024-1938
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Small businesses established in another EU Member State that use the cross-border SME exemption in Poland under art. 113a of the VAT Act and hold an EX identification number.
No action — in force since 1 January 2025. EU-established small businesses using the SME exemption in Poland show their EX number on simplified invoices.
Rozporządzenie Ministra Finansów z dnia 22 grudnia 2024 r. (Dz.U. 2024 poz. 1938), amending the invoicing regulation of 29 October 2021, added § 3 pkt 3a with effect from 1 January 2025: an invoice for supplies exempt in Poland under the EU cross-border SME exemption (art. 113a ust. 1 of the VAT Act, for taxpayers established in another Member State) need contain only the data in pkt 1 lit. a–g plus the individual EX identification number (art. 113a ust. 2 pkt 2) that the supplier obtained in its Member State of establishment. It is the invoicing counterpart of Dz.U. 2024 poz. 1721 (pl-vat-eu-sme-scheme-2024).
What changed in detail
The Minister of Finance regulation of 22 December 2024 (Dz.U. 2024 poz. 1938), published on 27 December 2024, amends the invoicing regulation of 29 October 2021 (Dz.U. 2021 poz. 1979) with effect from 1 January 2025.
It adds § 3 pkt 3a, a reduced-content invoice for supplies of goods or services exempt from VAT in Poland under art. 113a(1) of the VAT Act, the cross-border exemption for small businesses established in another Member State. Such an invoice need contain only:
- the data listed in § 3 pkt 1 lit. a–g of the regulation; and
- the individual identification number referred to in art. 113a(2)(2) of the Act, the EX number that the supplier obtained in its Member State of establishment.
The regulation is the invoicing counterpart of the Act of 8 November 2024 (Dz.U. 2024 poz. 1721), which opened the Polish exemption to EU-established small businesses from the same date. It also implements Council Directive (EU) 2020/285.
What it means
The rule is still in force, but in amended wording. The Minister of Finance and Economy regulation of 7 December 2025 (Dz.U. 2025 poz. 1742), in force from 1 February 2026 alongside mandatory KSeF, rewrote § 3 pkt 3a. The invoice now carries the data in pkt 1 lit. a–c and cb–g plus the supplier’s EX number. The same regulation added lit. cd: where the buyer is itself exempt under art. 113a(1), the invoice shows the buyer’s EX number.
So the EX number remains the key identifier on these invoices, now for buyers as well as sellers. The exemption itself is described in Poland opens its small-business VAT exemption to EU sellers. Its Polish limit rose to PLN 240,000 in 2026 (threshold change).
Proof
dostawę towarów lub świadczenie usług zwolnionych od podatku na podstawie art. 113a ust. 1 ustawy powinna zawierać dane, o których mowa w pkt 1 lit. a–g, oraz indywidualny numer identyfikacyjny, o którym mowa w art. 113a ust. 2 pkt 2 ustawysupplies of goods or provision of services exempt from tax under Article 113a(1) of the Act must contain the data referred to in point 1 lit. a–g, and the individual identification number referred to in Article 113a(2)(2) of the Act
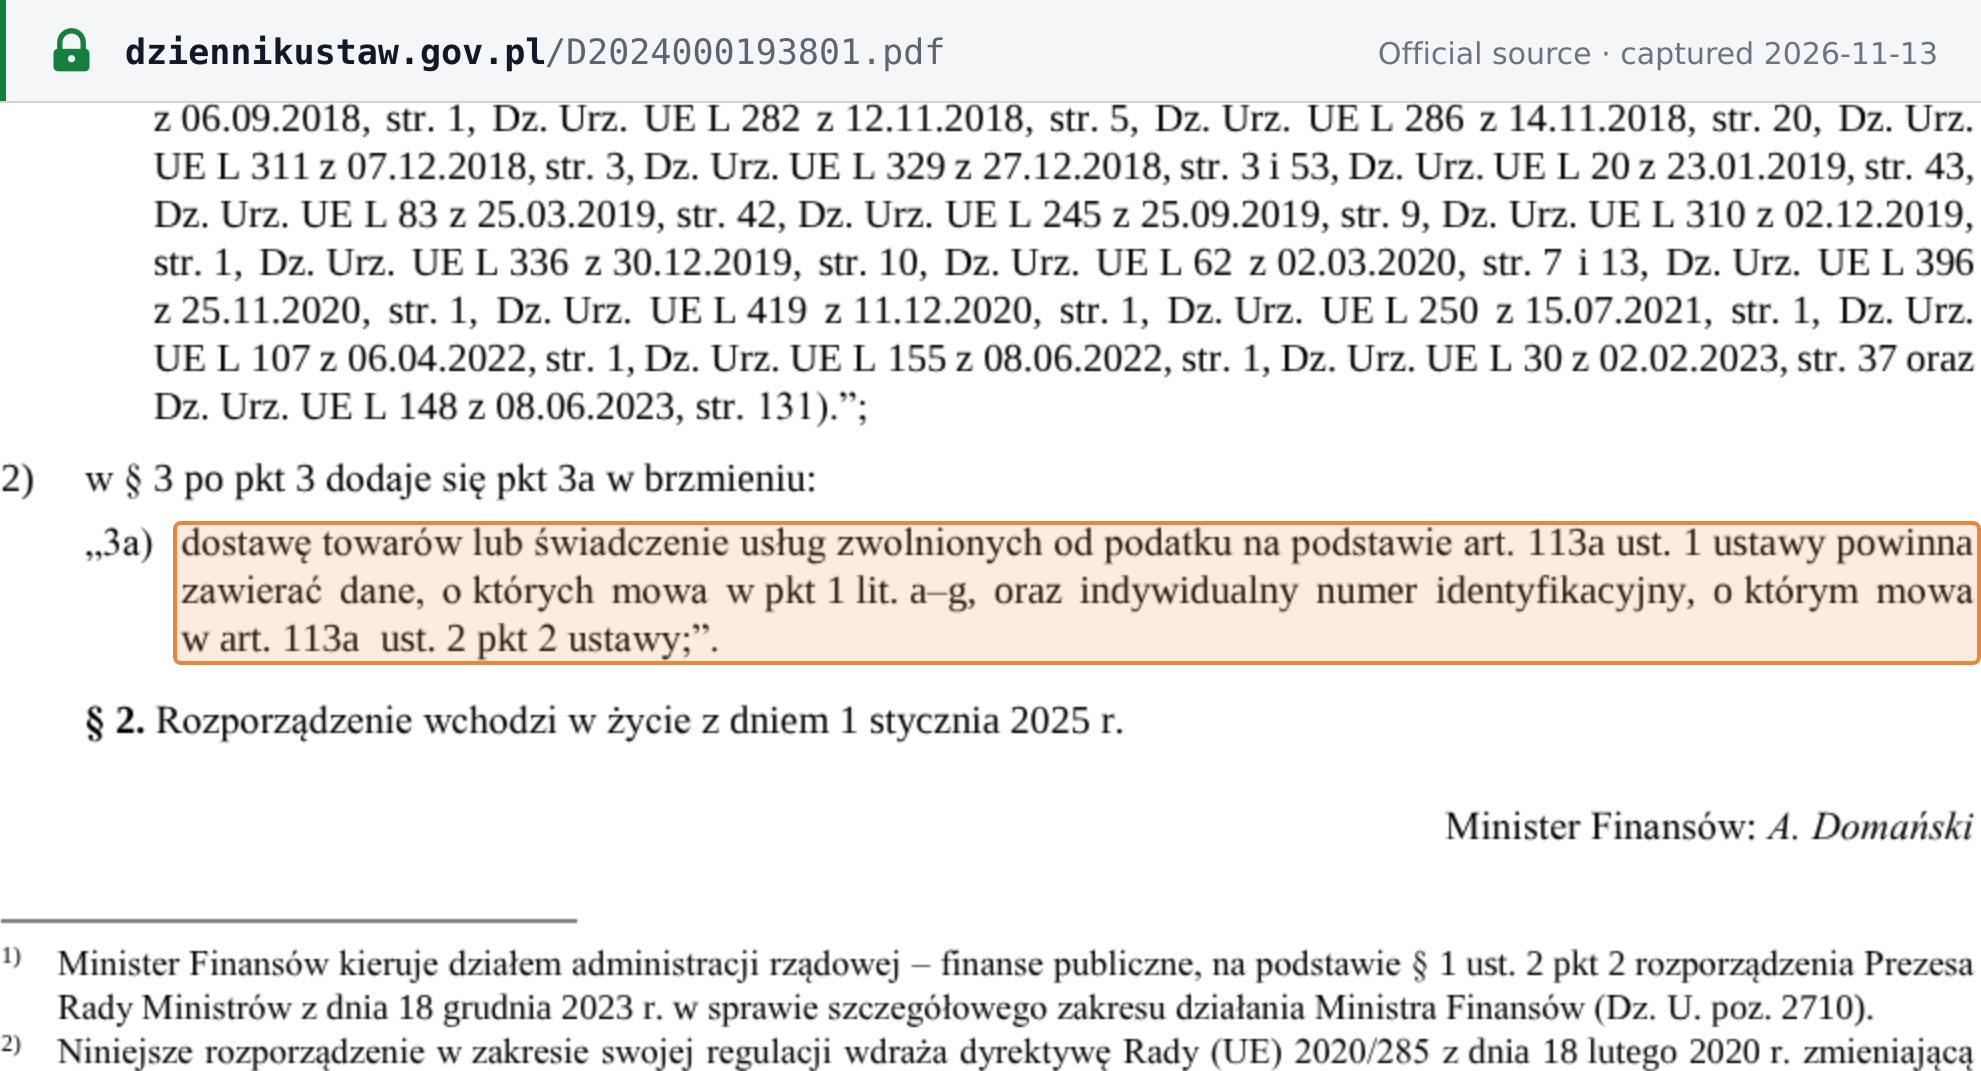 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2024 poz. 1938 · Rozporządzenie Ministra Finansów z dnia 22 grudnia 2024 r. · dziennikustaw.gov.pl