Poland raises the small-business VAT exemption threshold to PLN 240,000 from 1 January 2026
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- Plan ahead
- Announced
- 7 July 2025
- Effective
- 1 January 2026
- Instrument
- PL-ACT-DU-2025-896
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Polish businesses with annual sales up to PLN 240,000, especially those between PLN 200,000 and PLN 240,000 in 2025, and EU-established small businesses using the art. 113a exemption in Poland.
Small businesses with Polish sales between PLN 200,000 and PLN 240,000 can now use (or return to) the art. 113 exemption; monitor turnover against the PLN 240,000 limit.
Ustawa z dnia 24 czerwca 2025 r. (Dz.U. 2025 poz. 896) raised the small-business VAT exemption threshold in art. 113 ust. 1 of the VAT Act from PLN 200,000 to PLN 240,000 with effect from 1 January 2026. Under the transitional Art. 2, taxpayers whose 2025 sales (or pro-rated sales, for businesses started in 2025) were above PLN 200,000 but not above PLN 240,000 may use the exemption from 2026. Because the EU cross-border SME exemption (art. 113a) is capped at the art. 113 ust. 1 amount, the PLN 240,000 limit (alongside the EUR 100,000 EU-wide cap) also applies to EU-established businesses using the exemption in Poland.
What changed in detail
The Act of 24 June 2025 amending the VAT Act (Dz.U. 2025 poz. 896), published on 7 July 2025 and in force from 1 January 2026, amends art. 113(1) of the VAT Act. It replaces “kwoty 200 000 zł” with “kwoty 240 000 zł”. A business established in Poland is exempt from VAT if its sales, excluding tax, did not exceed PLN 240,000 in either the previous or the current tax year.
Under the transitional Art. 2:
- a Polish business whose 2025 sales were above PLN 200,000 but not above PLN 240,000 may use the exemption from 2026;
- the same applies to a business that started in 2025, measured on sales pro-rated to its period of activity;
- under Art. 2(3), the transition also applies to taxpayers using the art. 113a exemption.
The EU cross-border SME exemption in art. 113a caps Polish sales at the amount in art. 113(1). So the PLN 240,000 limit now applies to EU-established businesses too, alongside the EUR 100,000 EU-wide turnover cap.
What it means
The PLN 240,000 threshold is in force. It appears in art. 113(1) of the consolidated VAT Act (Dz.U. 2026 poz. 1263).
The base the threshold is measured against changes next. The Act of 4 September 2026 (Dz.U. 2026 poz. 1270) adds art. 113(1a) from 1 January 2027. Intra-Community transfers of own goods under art. 13(3) will count towards sales value for exempt taxpayers, and art. 113a is aligned. Sales for 2026 are still measured under the current rules (details). EU sellers should read this with the EU SME scheme.
Proof
w art. 113 w ust. 1 wyrazy „kwoty 200 000 zł” zastępuje się wyrazami „kwoty 240 000 zł”in art. 113(1), the words ‘amount of PLN 200,000’ are replaced by the words ‘amount of PLN 240,000’
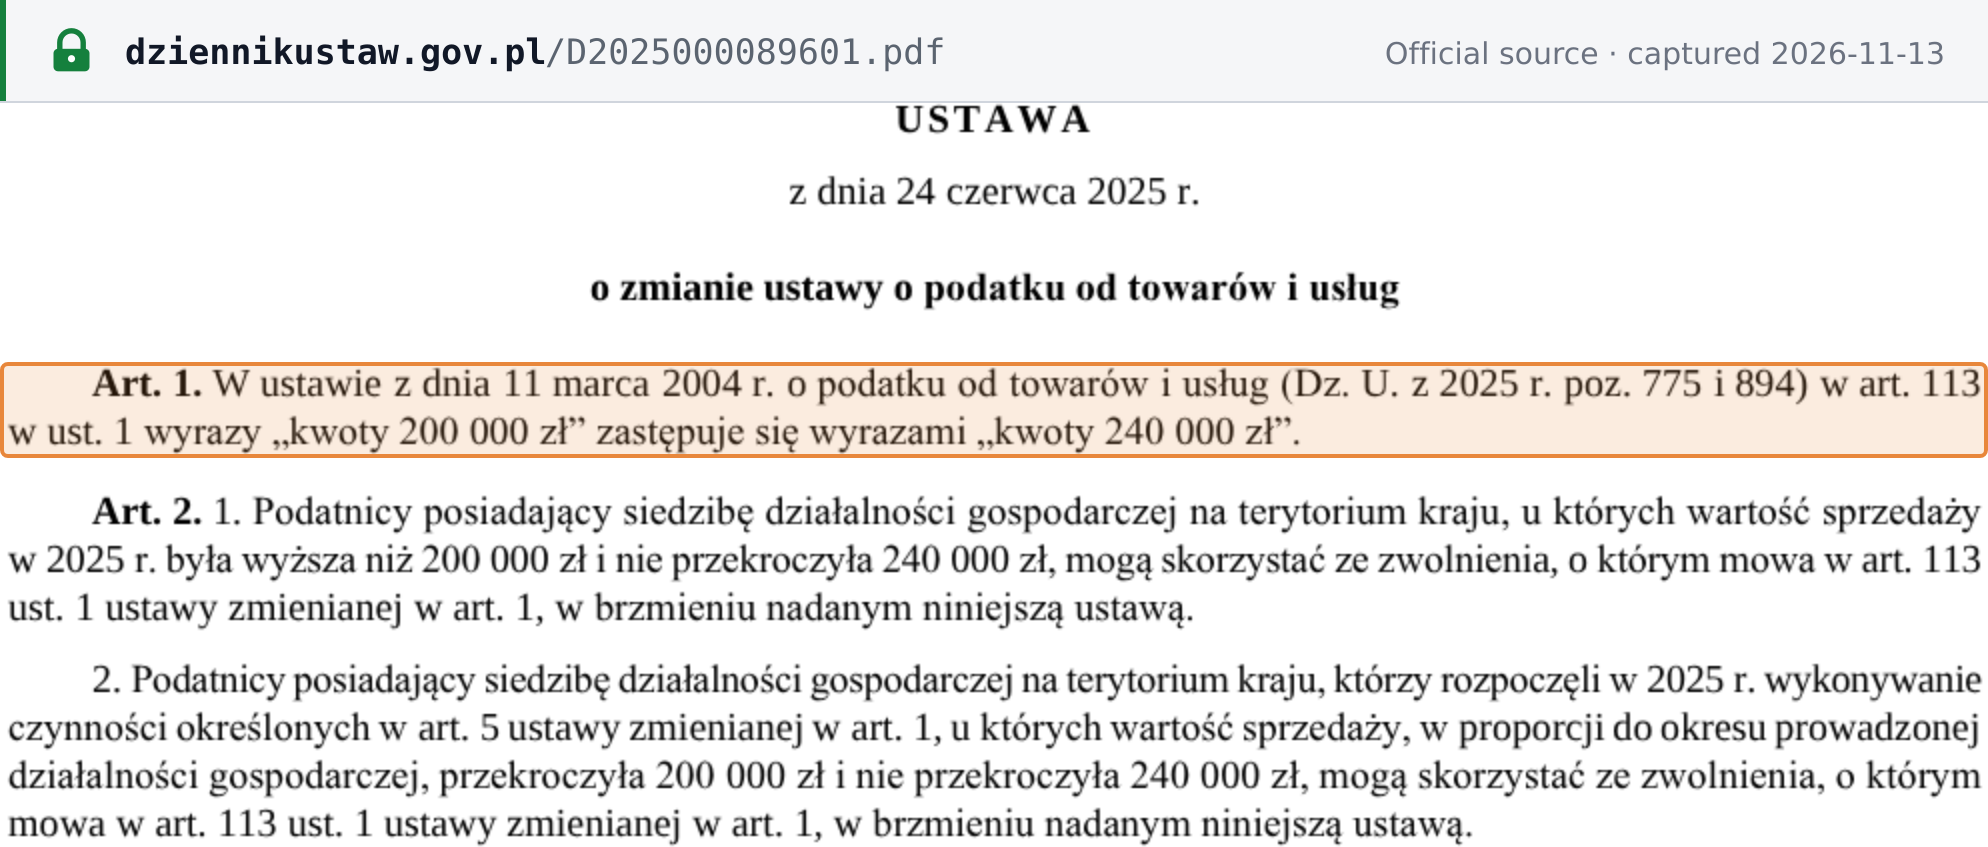 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2025 poz. 896 · Ustawa z dnia 24 czerwca 2025 r. · dziennikustaw.gov.pl