South Africa puts new foreign donor funded projects into a single VAT branch per implementing agency
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 24 December 2024
- Effective
- 1 January 2025
- Instrument
- ZA-ACT-42-of-2024
- Authority
- Parliament of the Republic of South Africa
- Verified
- Fetched from official source · high confidence
Implementing agencies registered for VAT in respect of foreign donor funded projects under the proviso to s 50(1) of the VAT Act.
No action required — in force since 1 January 2025. Implementing agencies administering foreign donor funded projects registered after 1 January 2025 must use a single separate branch registration; those with existing multi-branch registrations as at 31 December 2024 may retain them or elect to consolidate.
Taxation Laws Amendment Act 42 of 2024 (GG 51826, 24 December 2024) substituted s 50(2A) of the Value-Added Tax Act 89 of 1991 (s 50 of the Amendment Act, from 1 January 2025). Foreign donor funded projects registered on or after 1 January 2025 must be registered in a single separate branch of the implementing agency, and agencies with projects registered by 31 December 2024 may keep their separate branches or consolidate them. Agencies must keep separate accounts, an annual project list, a reconciliation for each tax period and Ministerial confirmation for each project. Section 46(1)(c) inserted s 8(30), which has no separate commencement date: when branches merge, the merged branch is deemed the same person, so the transfer of assets and liabilities is not a supply.
What changed in detail
Section 50 of the Taxation Laws Amendment Act 42 of 2024 (Government Gazette 51826, 24 December 2024) substitutes section 50(2A) of the Value-Added Tax Act 89 of 1991, from 1 January 2025.
An implementing agency:
- (a) must apply to register the activities for a foreign donor funded project registered under section 23 on or after 1 January 2025 as part of a single separate branch; or
- (b) for projects registered on or before 31 December 2024, may either keep each existing separate branch registration or apply to bring the project into the single separate branch.
The proviso requires the agency to keep, in addition to its other duties:
- an independent system of accounting for each project;
- an annual list of all registered projects with their reference numbers and start and end dates;
- a reconciliation, for each tax period, of the branch’s returned values with each project’s values; and
- written confirmation from the Minister that each project is established under an official development assistance agreement.
Section 46(1)(c) of the same Act inserts section 8(30): where branches merge into the single branch under section 50(2A)(b)(ii), the old branches and the merged branch are deemed to be one and the same person. Section 46 gives no separate commencement date for that paragraph.
What it means
The single-branch rule has applied since 1 January 2025. Taxation Laws Amendment Act 5 of 2026 (section 46) substituted the proviso to section 50(2A) from 1 April 2026, but only re-punctuated it: the four record-keeping duties are the same.
The point of the change is administrative. Agencies with many projects no longer need a VAT registration per project, but they now carry the burden of showing, within one branch, which supplies and refunds belong to which project. The per-period reconciliation is the requirement that refund audits will test. Agencies that merged their old branches can rely on section 8(30), so the merger itself is not a taxable supply.
Proof
(a) shall be required to make an application to the Commissioner to register the activities referred to in the proviso to subsection (1) as part of a single separate branch of the vendor in respect of such project registered in terms of section 23 on or after 01 January 2025; or (b) may, in respect of any of the activities referred to in the proviso to subsection (1) registered with the Commissioner on or before 31 December 2024— (i) retain an existing and separate branch registration; or (ii) make an application to the Commissioner to register the foreign donor funded project that has been registered separately as a single separate branch of the vendor: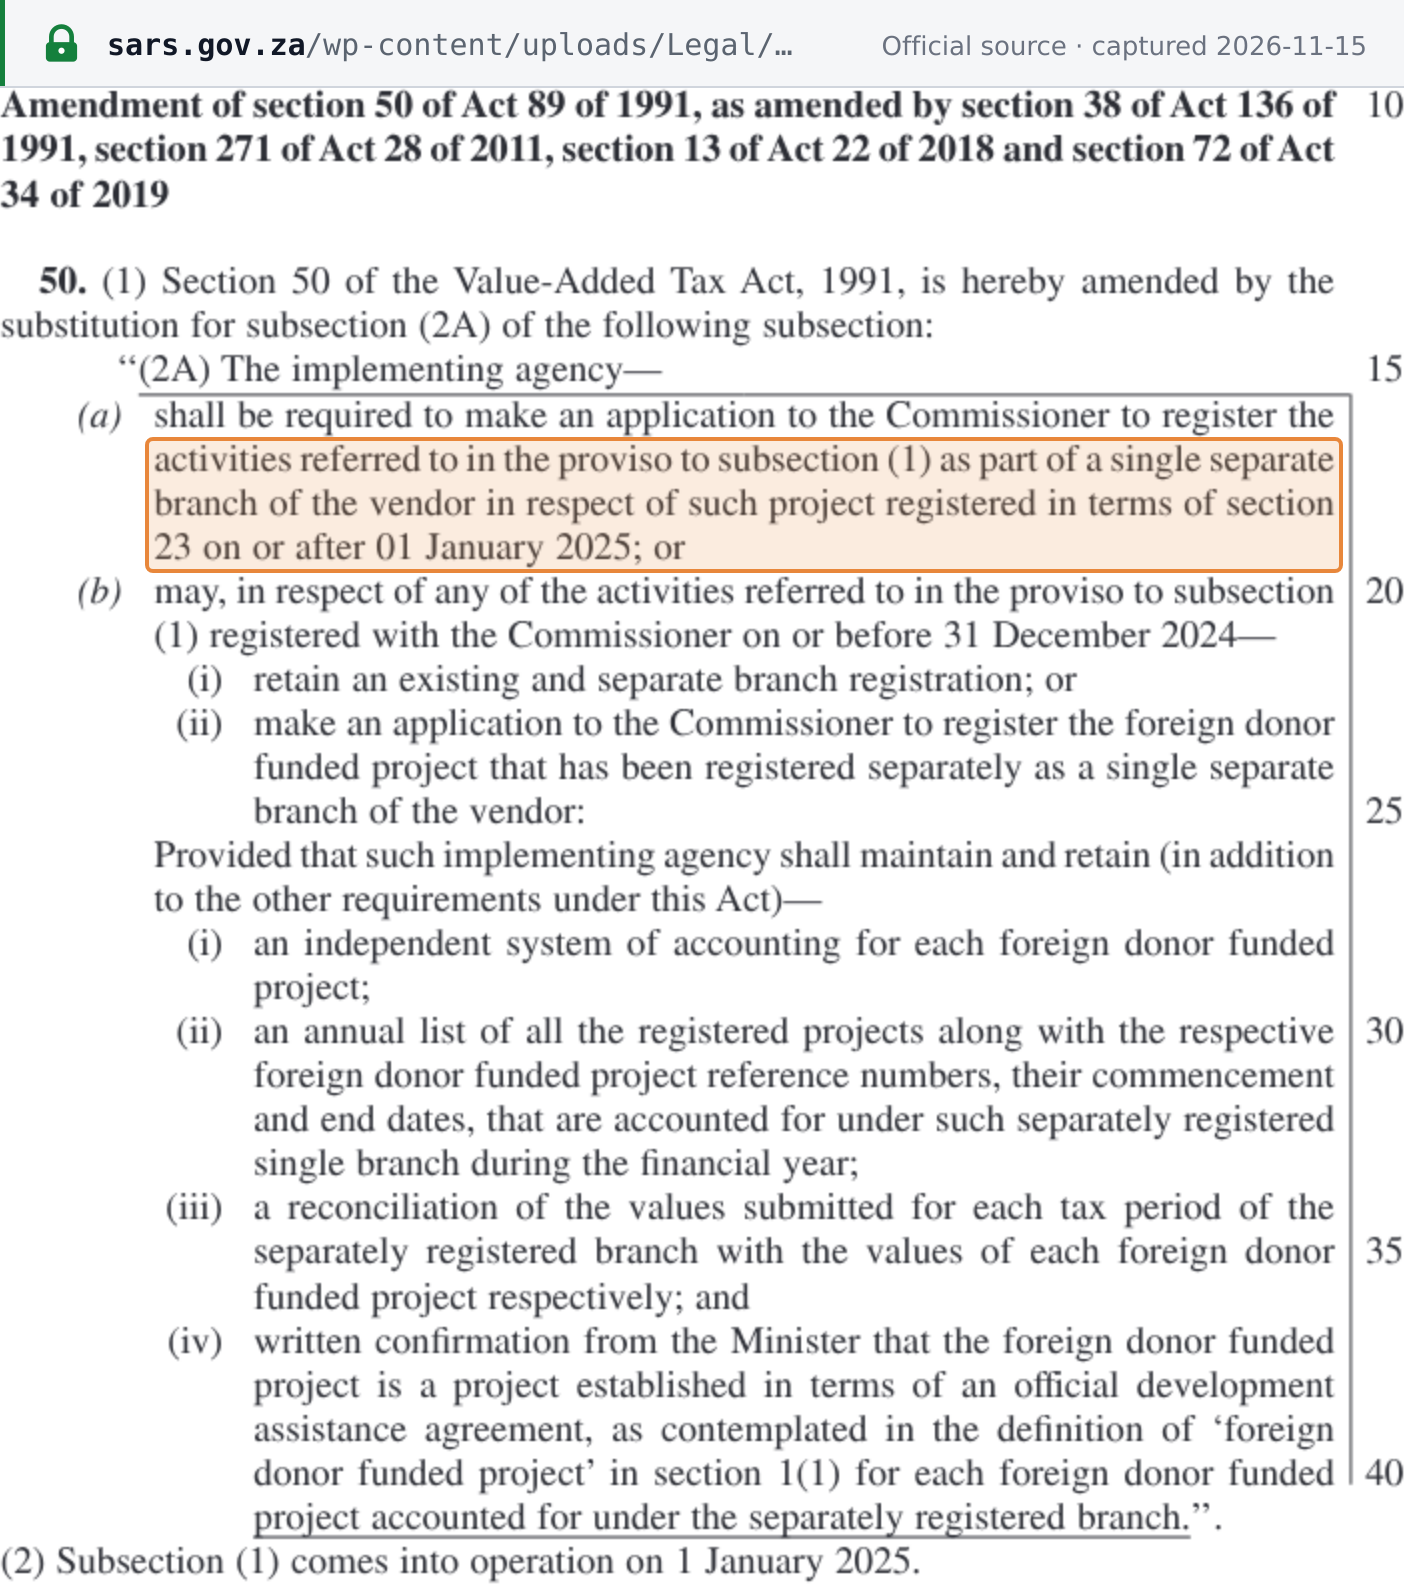 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Taxation Laws Amendment Act 42 of 2024, Government Gazette No. 51826, 24 December 2024 · www.sars.gov.za