BIR lets ecozone domestic market enterprises on the 5% GIE regime register for VAT (RR No. 13-2023)
This page records one dated change. For the rules in Philippines as they stand today, see the Philippines guide →
- Jurisdiction
- Philippines
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 10 November 2023
- Instrument
- PH-REVENUE-REGULATIONS-RR-13-2023
- Authority
- Bureau of Internal Revenue (BIR), Philippines
- Verified
- Fetched from official source · medium confidence
Registered Business Enterprises classified as Domestic Market Enterprises, located inside an economic or freeport zone and enjoying the 5% Gross Income Earned incentive during the CREATE Act transitory period.
No action — monitoring only. Only ecozone DMEs on the 5% GIE regime that elected VAT registration under this RR are affected, and their election is irrevocable for the rest of the transitory period.
BIR Revenue Regulations No. 13-2023 (issued 10 November 2023, signed by the Secretary of Finance on 31 October 2023) lets a Registered Business Enterprise classified as a Domestic Market Enterprise inside an economic or freeport zone keep the 5% Gross Income Earned incentive for the CREATE Act transitory period and register as a VAT taxpayer. To do so it needs an Investment Promotion Agency certification that the 5% GIE is in lieu of all taxes except VAT, and must waive the VAT exemption incentive. The waiver is irrevocable for the rest of the transitory period.
What changed in detail
Revenue Regulations No. 13-2023 implement Section 5, Rule 18 of the amended implementing rules of the CREATE Act (RA 11534). The regulations are dated 10 November 2023, and Secretary of Finance Benjamin E. Diokno signed them on 31 October 2023.
- Optional VAT registration (Sec. 2): a Registered Business Enterprise (RBE) classified as a Domestic Market Enterprise (DME) inside an economic or freeport zone may keep the 5% Gross Income Earned (GIE) incentive for the ten-year transitory period under Section 311(C) of the CREATE Act and register as a VAT taxpayer.
- Condition: the RBE needs a certification from its Investment Promotion Agency (IPA) stating that the 5% GIE is in lieu of all taxes except VAT. To get it, the RBE files a request letter and a notarised Deed of Waiver of Right to Avail of the VAT Exemption Incentive.
- Irrevocable: the waiver binds from the time it is made for the rest of the transitory period. The RBE then updates its registration with its Revenue District Office and is treated like a regular corporation for VAT.
- Reporting (Sec. 3): IPAs send the BIR a quarterly list of RBEs that hold the certification.
- No look-back (Sec. 4): an RBE that opts in cannot claim VAT refunds for transactions before the amended CREATE rules took effect.
- Effectivity (Sec. 7): the regulations take effect immediately after publication in a newspaper of general circulation or the Official Gazette. The publication date is not printed in the document.
What it means
The option still exists, but a later law has largely overtaken the reason for it. The CREATE MORE Act (RA 12066) made all local sales of RBEs subject to 12% VAT, whatever their income-tax regime or location. RR No. 9-2025 put that rule into practice and gave RBEs on the 5% GIE or SCIT regime their own option to register for VAT, with a three-year lock-in. RR No. 1-2026 later restated that option.
An ecozone DME that made the election under this regulation is still bound by it for the rest of the transitory period. A DME deciding now should start from the RR 9-2025 rules.
Proof
An RBE classified as DME which is located inside the Economic or Freeport Zone may retain the availment of the 5% GIE incentive during the ten (10) year transitory period under Section 311(C) of the CREATE Act and be allowed to register as a VAT taxpayer provided it secures from the concerned IPA a Certification specifically excluding VAT from the 5% GIE in lieu of all taxes incentive granted to it (Certification).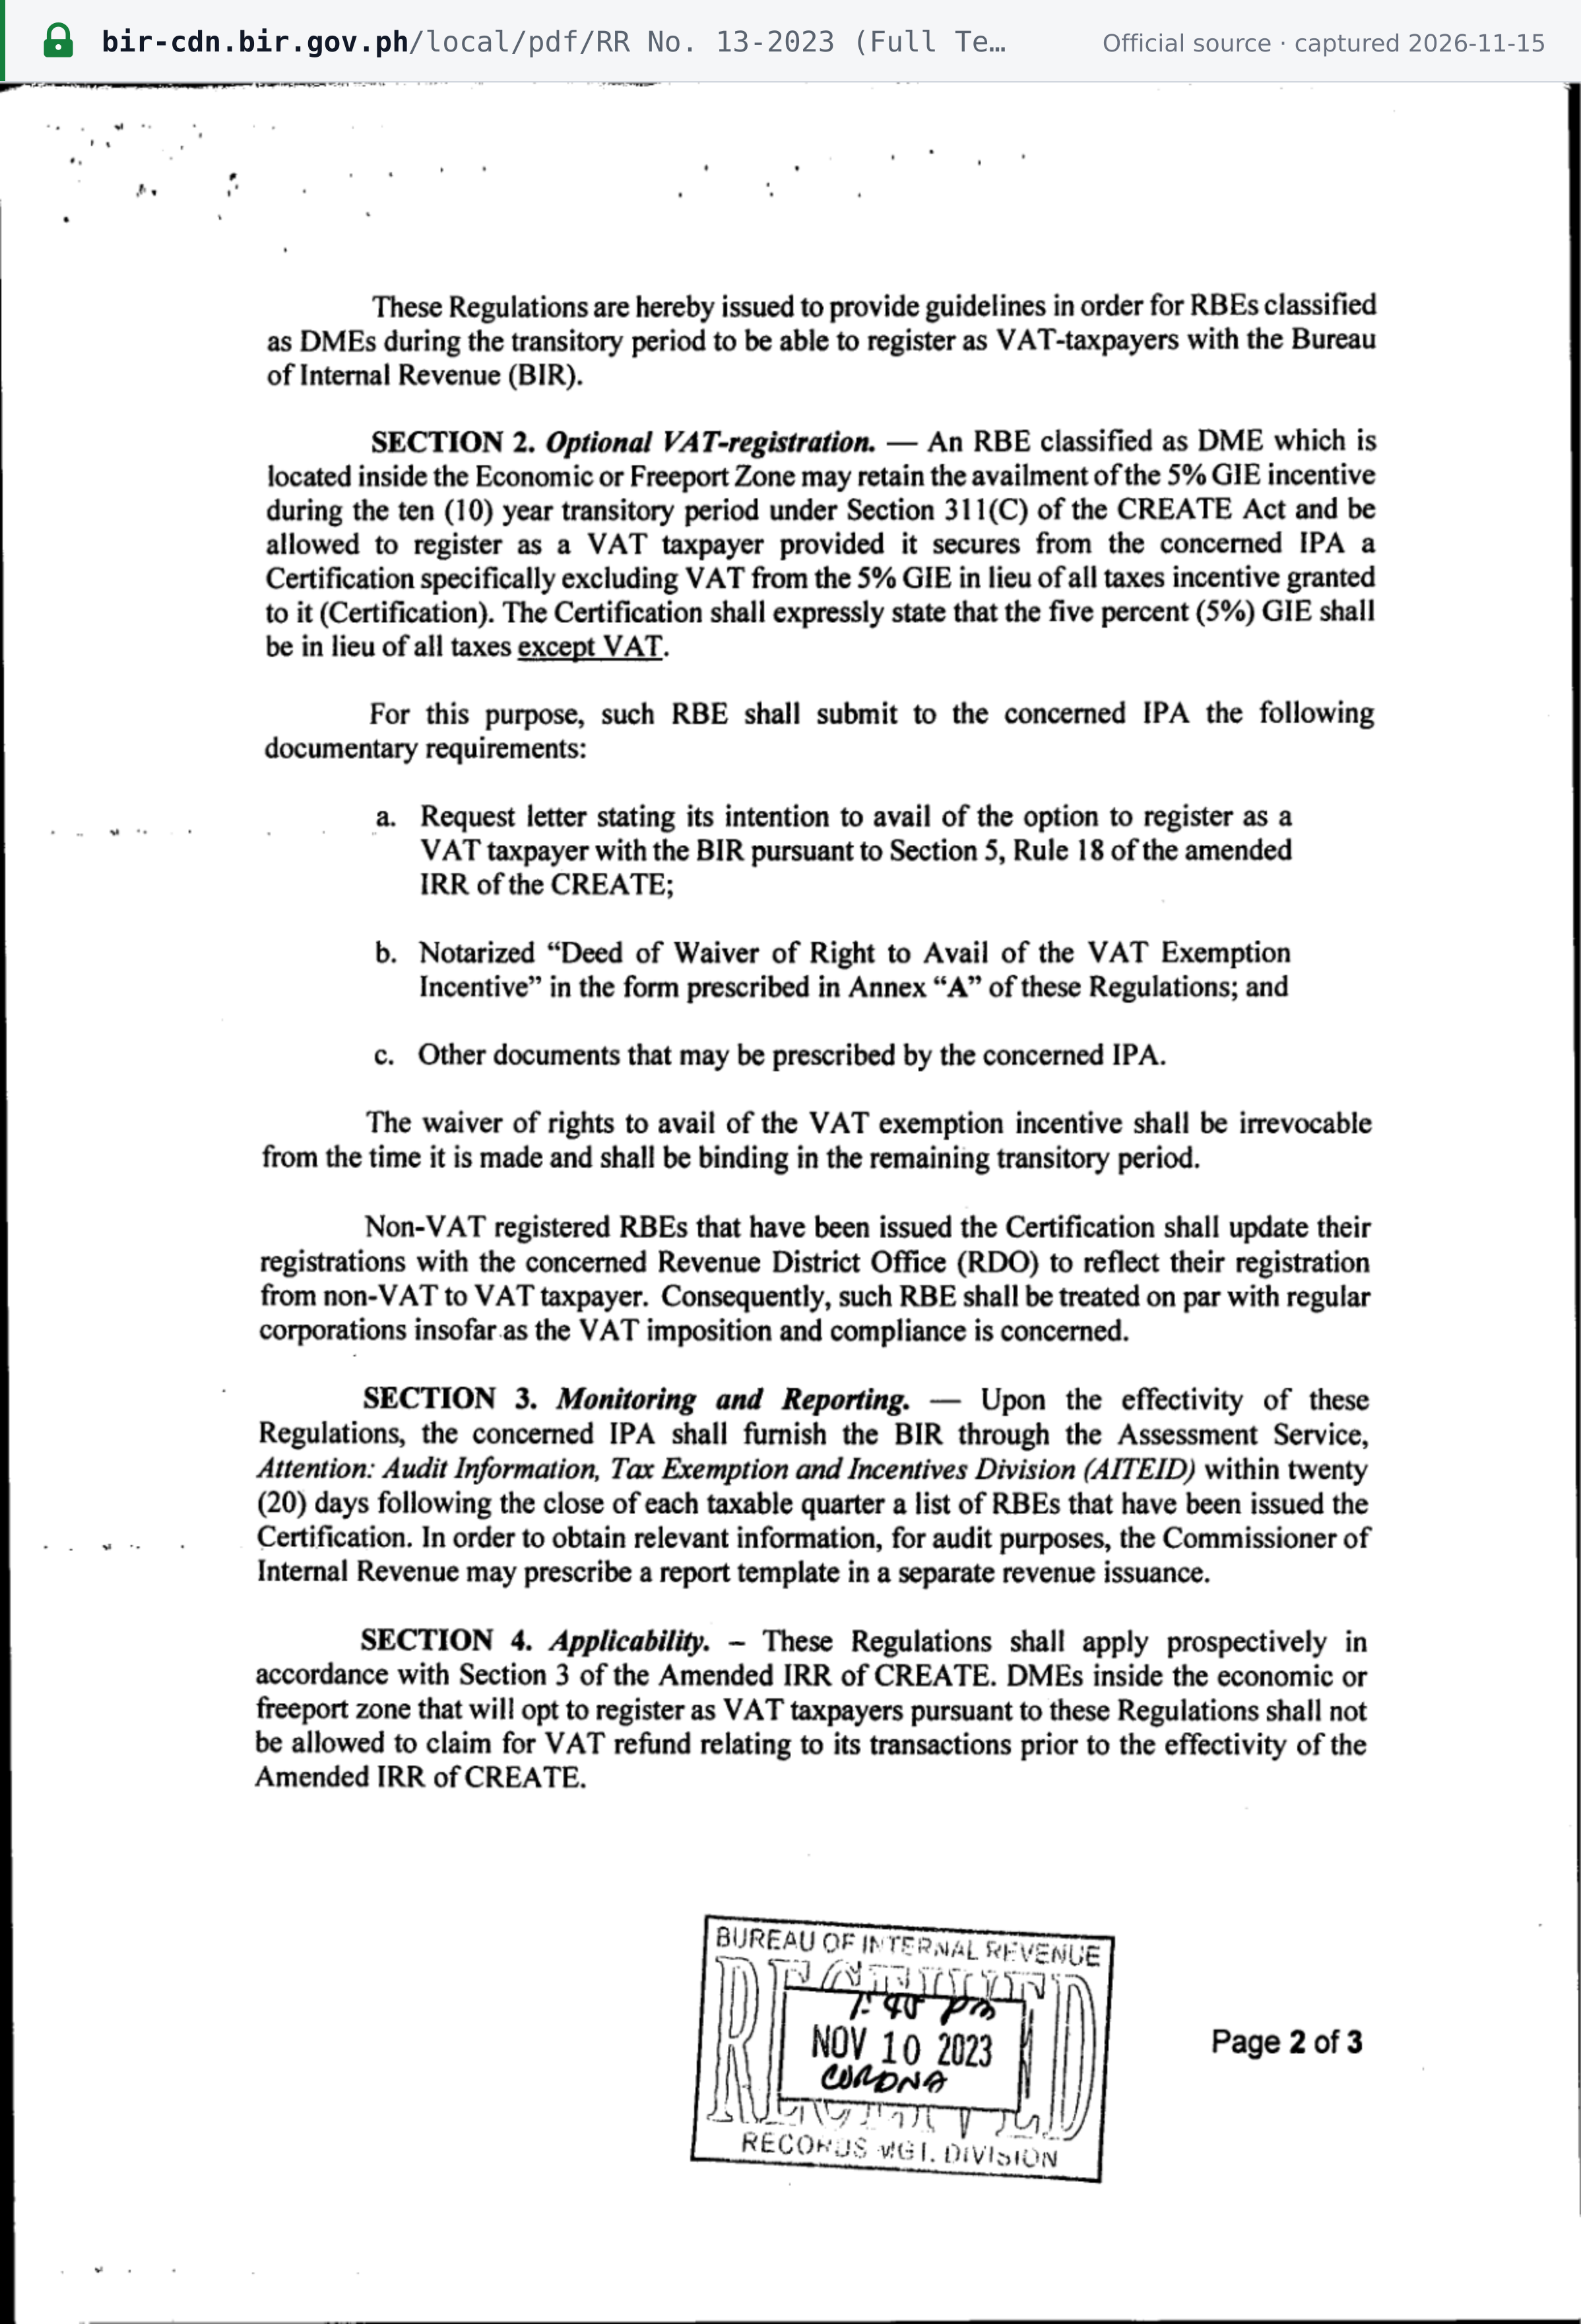 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Revenue Regulations No. 13-2023, Bureau of Internal Revenue, dated 10 November 2023, signed by the Secretary of Finance 31 October 2023, Sec. 2 (p. 2) · bir-cdn.bir.gov.ph